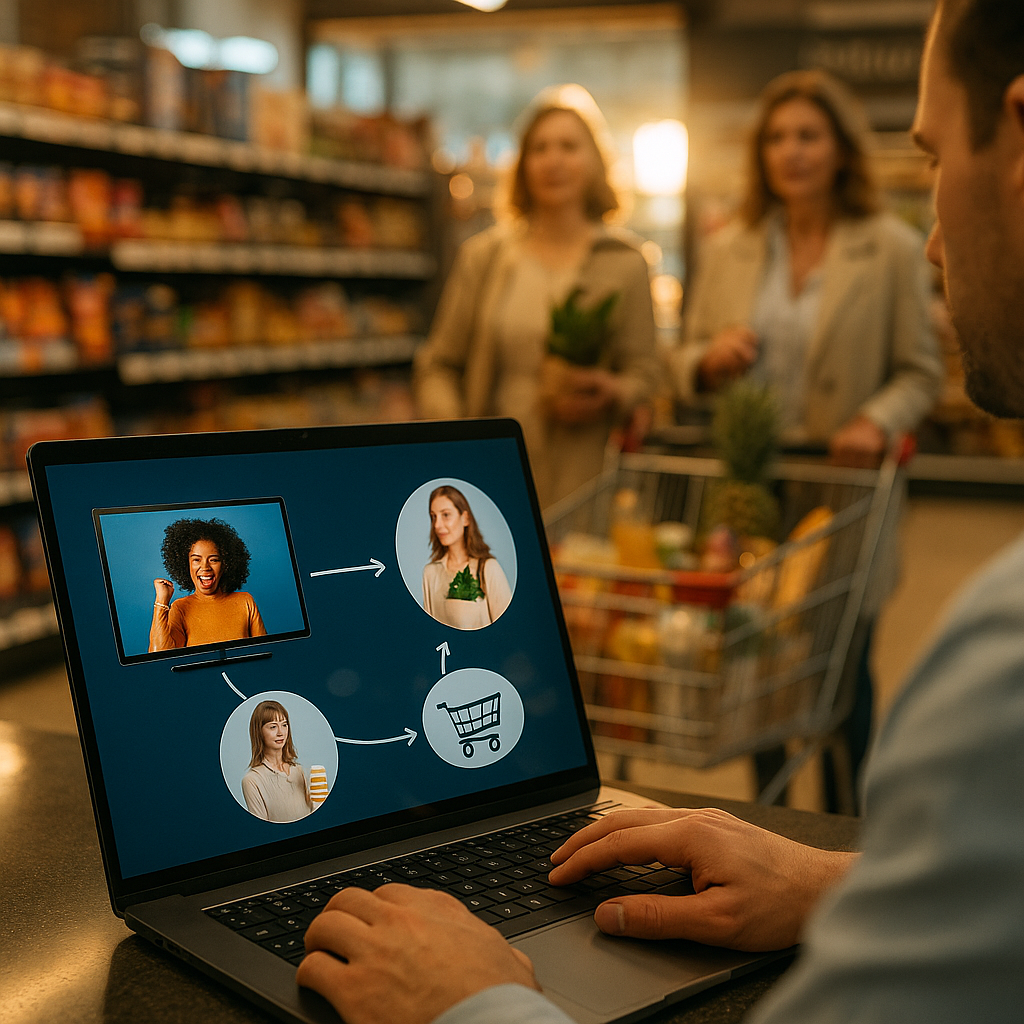
78% of marketers say they can’t reliably connect a CTV ad exposure to an in-store purchase. That gap isn’t a measurement footnote, it’s a budget problem. Identity resolution platforms promise to close it, but the category is crowded, inconsistent, and full of vendors claiming “true” identity when what they’re really selling is probabilistic guesswork. If you’re building a single customer view that has to survive contact with both streaming inventory and point-of-sale data, the platform you pick matters more than almost any other martech decision you’ll make this year.
Why Identity Resolution Is Suddenly a Boardroom Issue
Three years ago, identity resolution was a data science conversation. Now it’s a CMO conversation, and the reason is simple: CTV ad spend keeps climbing while third-party cookies keep dying. Marketers can no longer stitch together a customer journey with the tools that worked in 2019. Retail media, connected TV, and loyalty programs generate three completely different data shapes, and none of them naturally talk to each other.
In-store data lives in POS systems and loyalty card swipes. CTV data lives in device graphs and household IP mapping. Somewhere in between sits a mobile app, an email address, and a hashed phone number that may or may not belong to the same person who watched a pre-roll ad last Tuesday. Identity resolution platforms exist to bridge that mess, but “bridge” is doing a lot of heavy lifting in that sentence.
Most brands don’t have an identity problem. They have an identity fragmentation problem, spread across five vendors who were never designed to reconcile with each other.
What “Single Customer View” Actually Means Across CTV and In-Store
Let’s be precise, because vendors aren’t. A true single customer view links a household or individual identifier across channels with enough confidence to drive both measurement and activation. That means:
- A CTV impression can be tied to a known household graph, not just an IP address guess.
- An in-store transaction can be matched back to the same graph via loyalty ID, phone number, or email hash.
- The match rate is documented, auditable, and stable enough that finance trusts the attribution numbers it feeds.
Notice what’s missing from that list: perfection. No platform gets a 100% match rate, and any vendor promising it is either lying or defining “match” so loosely it’s meaningless. The honest conversation is about match rate quality, not match rate size. A 60% match rate built on deterministic data (hashed emails, loyalty IDs) beats a 90% match rate built on probabilistic device fingerprinting that regulators are increasingly skeptical of.
The Platforms: How They Actually Differ
There’s no shortage of vendors claiming to solve identity, but they cluster into a few real categories.
LiveRamp (RampID) remains the default choice for brands with heavy retail media and CTV footprints. Its strength is breadth: RampID connects across a massive number of publishers, retail media networks, and CTV platforms, which matters if your media mix spans Walmart Connect, Roku, and a regional grocery chain’s loyalty program. The tradeoff is cost and complexity. LiveRamp works best when you already have a mature customer data platform feeding it clean first-party data.
TransUnion (formerly Neustar) leans heavily on its data broker heritage, offering strong deterministic matching for offline and in-store reconciliation. If your single customer view priority is retail POS accuracy over CTV reach, TransUnion’s identity graph tends to outperform lighter-weight competitors.
Tapad (Experian) built its name on cross-device graphs and still performs well for CTV-heavy use cases, particularly where household-level targeting matters more than individual-level precision. It’s a reasonable middle ground for brands not ready for LiveRamp’s full enterprise commitment.
Zeotap and ID5 represent the European-influenced, privacy-forward tier. Both emphasize consented, first-party data pooling over broad probabilistic matching, which makes them attractive to brands operating under GDPR scrutiny or anticipating similar rules stateside. They generally trade some match rate breadth for cleaner compliance stories.
Google’s PAIR (Publisher Advertiser Identity Reconciliation) and Amazon’s clean room based identity tools sit in a different bucket entirely: walled garden identity that never leaves the platform. These aren’t full identity resolution platforms in the traditional sense, they’re closed-loop matching environments. Useful for measurement inside Amazon or YouTube, nearly useless for building a portable single customer view you own.
Build vs Buy: The CDP Question
Here’s the uncomfortable truth: a lot of brands don’t actually need a dedicated identity resolution platform. They need a properly configured CDP that already includes identity resolution as a feature. Segment, Tealium, and Adobe Real-Time CDP all bundle identity stitching capabilities that cover 70% of use cases for mid-market brands.
The calculus changes at scale. Once you’re running CTV campaigns across multiple DSPs and reconciling against in-store data from more than one retail partner, dedicated identity infrastructure starts paying for itself. That’s the same tradeoff explored in our context engines versus CDPs buyer’s checklist, and it applies almost identically here: complexity and scale justify dedicated tooling, everything below that threshold is overengineering.
Worth asking before you sign anything: does this platform actually reduce your tool sprawl, or does it just add a sixth vendor to a stack that already has five? Identity resolution platforms are notorious for creating new integration debt even as they solve the original matching problem.
Compliance Isn’t Optional Anymore
Identity resolution sits directly on top of the most legally sensitive data a brand holds. Get the consent trail wrong and you’re not just losing match rate, you’re exposed to regulatory action. The FTC has been explicit about scrutinizing data brokers and identity graphs that resell consumer information without clear consent mechanisms, and enforcement activity around data broker practices has only intensified.
This is where a lot of brands get burned. They evaluate identity platforms purely on match rate and cost, then discover during a legal review that the vendor’s data sourcing doesn’t hold up under audit. If you haven’t already mapped your consent trail before selecting an identity vendor, you’re building on sand.
The identity resolution vendor with the best match rate on the demo isn’t automatically the one that survives a legal audit six months later. Ask about data provenance before you ask about accuracy.
A Practical Evaluation Framework
Skip the vendor scorecards that weight everything equally. In practice, four criteria matter more than the rest combined:
- Deterministic match ratio. What percentage of matches come from hashed emails, phone numbers, or loyalty IDs versus probabilistic modeling? Push every vendor for this number specifically.
- CTV publisher coverage. Does the platform have direct integrations with your actual media mix, or does it rely on generic device graphs that degrade fast on connected TV?
- In-store data ingestion speed. Some platforms process POS data in near real time; others batch overnight. If you’re running time-sensitive promotions, that lag matters.
- Attribution handoff. Can the identity graph feed directly into your attribution dashboard without a manual export step? This is where most implementations quietly fail.
Run a 90-day pilot before committing to a multi-year contract. Match rates that look great in a sales deck often collapse once real, messy, first-party data hits the pipeline. Industry benchmarks tracked by eMarketer consistently show a gap of 15 to 20 percentage points between vendor-claimed and client-observed match rates, so build that skepticism into your evaluation timeline.
For brands running creator-driven CTV campaigns specifically, the identity challenge compounds. A technical build guide for cross-device creator attribution is worth reviewing alongside any identity platform shortlist, since the same identity graph often has to support both retail attribution and influencer program measurement simultaneously.
What This Means for Your Next Budget Cycle
Identity resolution isn’t a line item you set once and forget. Match rates decay as consumer behavior shifts and as platforms tighten data-sharing rules, so budget for annual re-evaluation, not a five-year lock-in. Treat the vendor relationship the way you’d treat a media buy: measured, renegotiated, and replaced if the numbers stop justifying the cost.
Frequently Asked Questions
What is identity resolution in marketing?
Identity resolution is the process of matching data points, such as email addresses, device IDs, loyalty numbers, and household identifiers, to a single, unified customer profile across channels and devices.
How is identity resolution different from a customer data platform?
A CDP stores and organizes first-party customer data, while identity resolution is the specific matching layer that links disparate identifiers into one profile. Many CDPs include identity resolution as a built-in feature, but dedicated identity platforms often offer broader match coverage for CTV and offline retail data.
Can identity resolution work without third-party cookies?
Yes. Most modern platforms rely on deterministic first-party signals like hashed emails, phone numbers, and loyalty IDs rather than cookies, which is precisely why demand has grown as cookie deprecation accelerates.
What match rate should brands expect between CTV and in-store data?
Match rates vary widely by vendor and data quality, but brands should expect deterministic match rates in the 40% to 65% range for CTV-to-in-store reconciliation, with probabilistic modeling pushing reported numbers higher at the cost of accuracy.
Is identity resolution compliant with privacy regulations?
It can be, but compliance depends entirely on the vendor’s data sourcing and consent mechanisms. Brands should verify that any identity platform documents clear consumer consent and complies with applicable regulations before activation.
Next step: before you sign a contract, run a 90-day pilot with your messiest real data, not the vendor’s clean demo set, and demand the deterministic match ratio in writing.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →