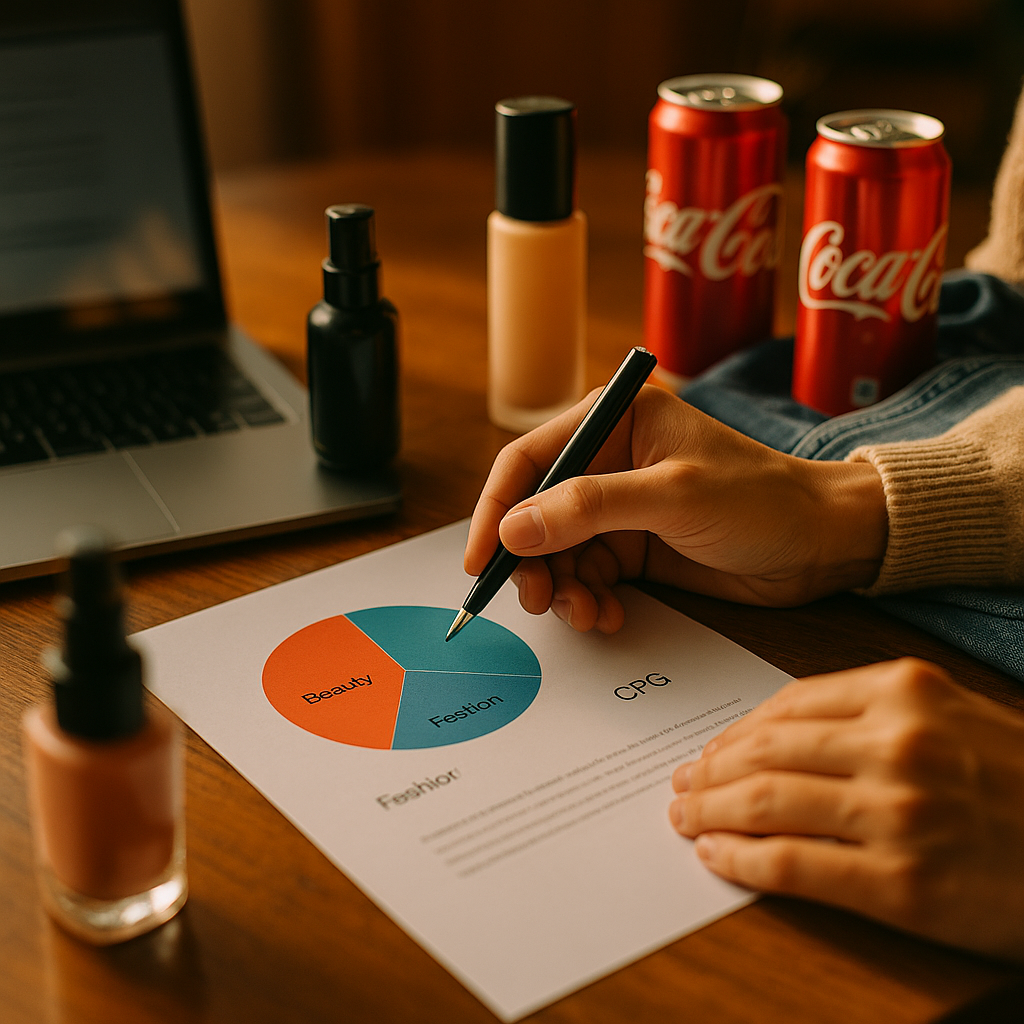
Beauty brands will spend an average of 24% of total marketing budget on creator partnerships next year. Fashion sits at 19%. CPG, historically the laggard, is closing the gap fast at 16%. If your 2027 planning still treats influencer spend as a rounding error on the media plan, you’re already behind. The 2027 creator spend benchmarks emerging from early planning cycles show a category that has stopped being experimental and started being structural.
This isn’t another “influencer marketing is growing” piece. You already know that. What you need is the number to defend in the budget meeting, broken down by vertical, so you can tell your CFO whether you’re underfunded, overexposed, or right on target.
Why Vertical Matters More Than Category Averages
Blended industry averages are almost useless for planning. A beauty brand and a canned soup company do not operate the same creator economics, yet most benchmarking reports lump them together under one “influencer marketing” umbrella. The result: brands either overspend chasing a beauty-level percentage they don’t need, or underspend because a flat 10% sounded reasonable.
Product consideration cycles, purchase frequency, and content shelf life all differ wildly by vertical. Beauty products get discovered through tutorials and dupes content that stays relevant for months. CPG relies on repetition and habit, meaning creator content needs constant refresh. Fashion lives and dies by seasonality and drop cycles. Each of those dynamics changes how much you should be spending, and where.
Brands benchmarking against the wrong vertical consistently misallocate 20 to 30% of creator budget, either overfunding awareness content in a category that needs conversion, or underfunding retention in a category built on repeat purchase.
Beauty: The Category That Set the Ceiling
Beauty remains the benchmark everyone else measures against, and for good reason. Brands like e.l.f. Cosmetics and The Ordinary built entire growth strategies on creator-first launches rather than traditional media. Early 2027 planning data suggests beauty brands will allocate between 22% and 28% of total marketing budget to creator partnerships, with the bulk going toward mid-tier creators (50,000 to 500,000 followers) who deliver higher engagement rates than mega-influencers at a fraction of the cost.
What’s shifting for next year isn’t the top-line percentage, it’s the mix. Beauty brands are pulling back on one-off gifting campaigns and reinvesting in always-on ambassador programs. That mirrors the thinking in always-on community budget strategies, where retention spend gets ring-fenced separately from campaign bursts so it survives the first round of cuts.
Dupe culture and ingredient-led content (think “skinfluencers” dissecting formulations) have also pushed beauty brands toward longer creator contracts. A single viral TikTok can sell out a product in 48 hours, but the brands winning repeatedly are the ones with creators under retainer, not one-off deals.
What’s the realistic beauty benchmark for a mid-size brand?
If you’re a challenger beauty brand doing under $50 million in annual revenue, budget conversations should start around 20% of marketing spend directed at creators, with at least 60% of that going to recurring partnerships rather than single-post deals. Below that threshold, you risk looking like a brand sampling the channel rather than committing to it.
Fashion Spend Is Splitting Into Two Camps
Fashion’s 2027 benchmark sits lower than beauty’s, averaging 17% to 21% of marketing budget, but the number hides a split that matters more than the average itself. Fast fashion and accessible-luxury brands are increasing creator spend aggressively, chasing TikTok Shop and livestream shopping formats. Heritage luxury brands are pulling back on volume and reinvesting in fewer, higher-production partnerships with creators who carry genuine editorial credibility.
Both camps are converging on one thing: content repurposing. Fashion brands can no longer justify paying for a single piece of creator content that lives on one platform for one campaign. The brands getting the best return are treating every creator asset as a content library, feeding it into paid social, email, and even product pages. That’s the logic behind tracking your content repurposing ratio as a core efficiency metric rather than an afterthought.
Platform risk is another factor fashion brands can’t ignore heading into next year. A disproportionate share of fashion creator spend still runs through TikTok, which means scenario planning around platform risk budgets isn’t optional anymore, it’s a line item your finance team will ask about directly.
CPG Finally Gets Serious
CPG has been the slowest mover in creator marketing, largely because attribution has always been harder. Nobody tracks a single social post to a grocery store purchase the way a beauty brand tracks a direct-to-consumer sale. But the 2027 numbers show CPG closing in, with projected creator allocations between 13% and 18% of marketing budget, up from roughly 9% just two years ago.
What changed? Retail media integration and better affiliate tooling. Brands can now stitch creator content to loyalty card data and retail media impressions, giving CPG marketers something closer to the attribution clarity beauty and fashion have had for years. That’s also why disputes over whose sale gets credited are becoming more common, and why frameworks for resolving affiliate attribution disputes between sales and marketing teams are showing up in more procurement conversations.
CPG’s creator spend also skews heavily toward nano and micro creators. Food, beverage, and household brands have found that authenticity at small scale (a parent batch-cooking with your sauce, a college student reviewing your energy drink) outperforms celebrity-tier endorsements for driving trial. Expect CPG budgets to keep favoring volume over prestige through next year.
How should CPG brands benchmark against retail media?
Increasingly, not separately. The smartest CPG teams are modeling creator spend directly against retail media ROAS, since both compete for the same incremental sales dollar. If you haven’t built that comparison yet, the creator program P&L approach to benchmarking CPA against retail media is worth adopting before your next budget cycle.
The Budget Allocation Question Nobody Answers Clearly
Here’s where most benchmark reports fall short: they tell you the percentage of total marketing budget, but not how to split it across creator tiers. That’s the decision that actually determines your ROI.
Across all three verticals, the 2027 pattern looks roughly like this:
- Beauty: 15% celebrity/macro, 55% mid-tier, 30% micro/nano
- Fashion: 20% celebrity/macro, 45% mid-tier, 35% micro/nano
- CPG: 5% celebrity/macro, 35% mid-tier, 60% micro/nano
Notice the inverse relationship. CPG leans hardest into nano and micro creators because trust and relatability drive purchase decisions for everyday products. Beauty and fashion still value reach for launch moments, but even they are shifting weight toward mid-tier creators as cost-per-engagement data improves. If you need a sharper read on where your spend should land by tier, the CPE benchmarks by tier framework breaks this down with harder numbers than a vertical average can provide.
Building the Internal Case for Next Year’s Number
Knowing the benchmark is one thing. Getting it approved is another. If you’re walking into a planning meeting with a percentage increase request, don’t lead with “the industry is spending more.” Finance teams don’t fund industry trends, they fund projected returns.
Tie your ask to a specific framework. Brands that successfully grow creator budgets year over year tend to use a CPA-based framework rather than a vague “brand awareness” pitch. Show the cost per acquisition trendline, compare it against your paid social CPA, and let the number argue for itself.
It also helps to have your operational story straight before you ask for more money. A larger creator budget without the infrastructure to deploy it well just creates waste. If headcount or tooling is the real constraint, that’s a separate conversation worth having using a quarterly expansion roadmap rather than bundling it into the media budget ask.
External validation helps too. Point to eMarketer’s category spend projections or Statista’s influencer marketing data to show you’re not pulling numbers out of thin air. Platforms like Meta Business and TikTok Ads also publish benchmark guidance that can corroborate your internal modeling, which carries weight with finance teams skeptical of agency-sourced stats.
One compliance note that cuts across every vertical: as creator spend grows, so does regulatory scrutiny. The FTC’s disclosure guidelines aren’t getting looser, and UK brands need to keep an eye on ICO guidance around data use in creator campaigns too. Budget growth without a parallel compliance review is how brands end up explaining themselves to regulators instead of customers.
Next Step
Pull your current creator spend as a percentage of total marketing budget, compare it against your vertical’s benchmark range above, and flag the gap before your next planning cycle starts. If you’re more than five points off, that’s not a rounding error, it’s a strategic conversation you need to have this quarter, not next year.
FAQs
What percentage of marketing budget should brands allocate to creator partnerships?
Beauty brands should target 22% to 28% of total marketing budget, fashion brands 17% to 21%, and CPG brands 13% to 18%. These ranges reflect projected 2027 planning benchmarks and will vary based on brand size, DTC versus retail distribution, and current program maturity.
Why do beauty brands spend more on creators than CPG brands?
Beauty products have shorter consideration cycles and stronger visual discovery behavior, making creator content directly influence purchase decisions. CPG relies more on habitual repeat purchase and has historically had weaker attribution tools, though that gap is narrowing with retail media integration.
How should brands split budget between celebrity, mid-tier, and micro creators?
CPG brands should weight heavily toward micro and nano creators (around 60% of spend) for trust-driven trial. Beauty and fashion brands can maintain stronger mid-tier allocation (45 to 55%) while reserving 15 to 20% for macro or celebrity talent during major launches.
What’s the biggest mistake brands make when benchmarking creator spend?
Using blended, cross-industry averages instead of vertical-specific data. This leads to misallocated budget, either overspending on reach in categories that need conversion-focused content, or underfunding the recurring partnerships that drive retention.
How do I justify a bigger creator budget to finance leadership?
Lead with cost-per-acquisition comparisons against existing paid channels rather than general industry growth claims. Finance teams respond to projected ROI, not trend narratives, so anchor your request in a CPA or ROAS framework they already trust.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →