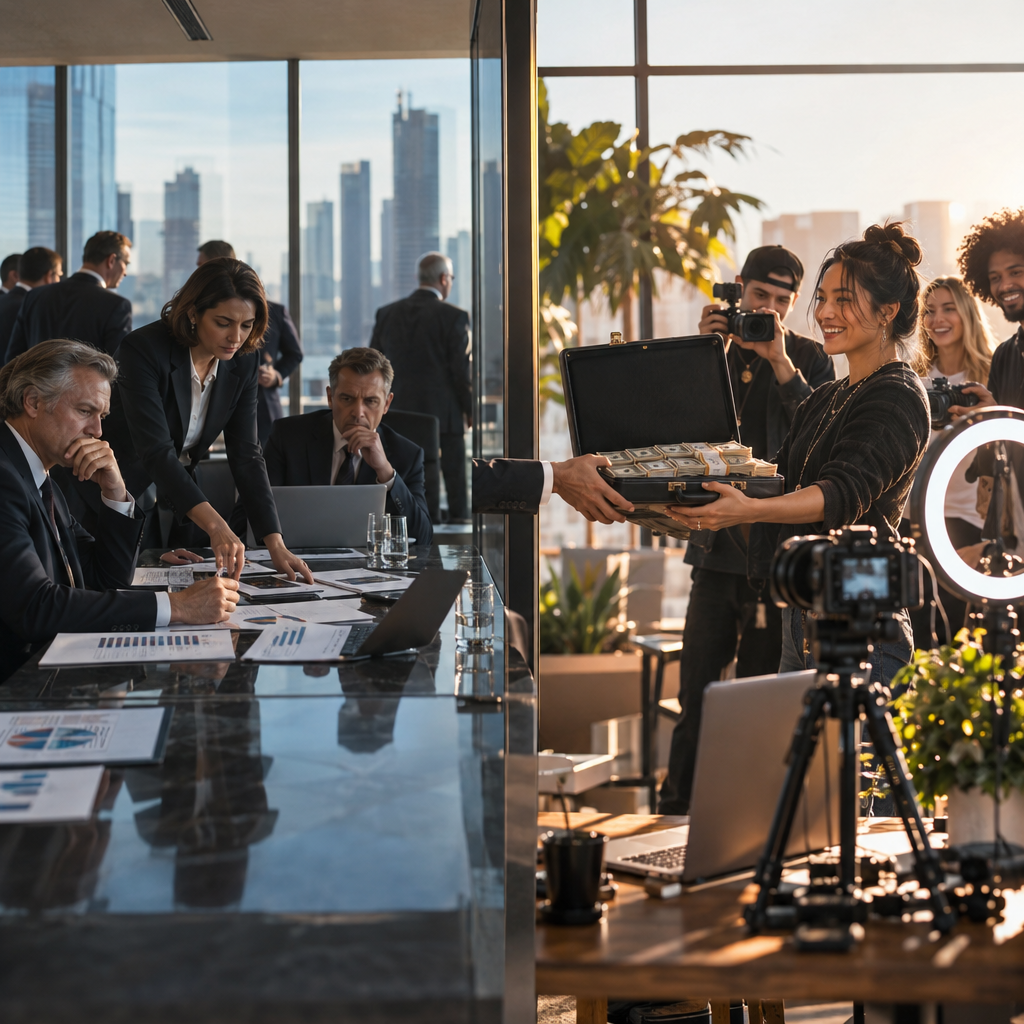
One holding company just cut thousands of jobs. Another merged with its biggest rival. Meanwhile, creator-first shops with a fraction of the headcount are walking away with campaign budgets that used to belong to Madison Avenue by default. The Madison Avenue versus creator agencies fight isn’t theoretical anymore. It’s showing up in quarterly earnings calls, and the holding companies know it.
The Numbers Behind the Panic
WPP’s organic growth has been flat or negative for several consecutive quarters. Omnicom, fresh off its merger with Interpublic Group, is betting scale will solve a problem that scale didn’t create. The problem isn’t really about size. It’s about where brands think the smartest creative and media thinking now lives.
Influencer and creator marketing spend keeps climbing even as traditional ad agency retainers shrink. Industry estimates from eMarketer put creator economy ad spend on a trajectory that outpaces linear and even most digital display growth. That’s not a rounding error for a holding company that built its entire P&L on media commissions and retainer fees.
Brands aren’t abandoning Madison Avenue because the work got worse. They’re reallocating because creator agencies can move a campaign from brief to published content in days, not months.
Specialist shops like the ones we covered when CAA and WME signed creators directly are proof that talent representation and media buying are converging into a single competitive lane. That lane used to belong exclusively to the big six holding companies. It doesn’t anymore.
What WPP Is Actually Doing About It
WPP’s response has been a mix of acquisition and internal reinvention. The company has poured money into AI-driven production tools, partly to cut the cost of content creation and partly to answer the obvious question every CMO is asking: why does a 30-second spot still cost six figures when a creator can produce something with comparable engagement for a tenth of that?
WPP’s bet is that AI-assisted production plus data infrastructure will let it compete on speed without sacrificing the brand safety and measurement rigor that scared procurement teams actually want. That’s a reasonable bet, but the execution has been uneven. Our own reporting on AI adoption hitting 93 percent while production speed stalls shows the gap between tool adoption and actual output velocity. Buying the software isn’t the hard part. Rewiring the workflow around it is.
WPP has also been quietly building creator vetting and compliance layers into its offering, a direct response to brands getting burned by unvetted influencer partnerships. That’s smart positioning. Compliance is one area where legacy agencies still have a structural edge over scrappier creator shops, especially as regulatory scrutiny from bodies like the FTC and the UK’s ICO tightens around disclosure and data handling.
Omnicom’s Bet: Scale First, Specialization Second
Omnicom took the opposite approach. Instead of rebuilding from the inside, it merged with Interpublic Group to create a combined entity with enough scale to negotiate better platform rates and absorb smaller creator-focused agencies wholesale. The logic is straightforward: if you can’t out-innovate the nimble players, buy enough of them that scale becomes the moat again.
This is the same consolidation pattern we flagged in creator agency roll ups forcing brands to vet vendors harder. When a holding company acquires a creator shop, brands lose the thing that made that shop attractive in the first place: speed, specialization, and a founder-led point of view. Omnicom has to manage that tension carefully, or it risks paying premium prices for agencies that lose their edge the moment they’re folded into a larger reporting structure.
There’s also a simple math problem. Omnicom’s combined entity now represents a larger share of global ad spend, which sounds like leverage. But leverage with platforms like Meta and TikTok matters less when the actual creative and casting decisions are increasingly happening inside creator agencies that never touch a holding company contract.
Why Creator Agencies Keep Winning the Pitch
Ask any brand marketer who’s run a bake off between a traditional agency and a creator-focused shop in the last year, and the answer is consistent: speed and authenticity win, almost every time. Creator agencies don’t need six layers of account management to greenlight a concept. They often have direct relationships with the talent, which cuts negotiation time and reduces the risk of miscommunication between brand brief and final content.
Shops like VaynerMedia and OLIVER have built entire creator benches as a core service line rather than a bolt-on, something we detailed in how VaynerMedia and OLIVER redrew agency pricing. That pricing model, often a blended retainer plus performance fee instead of a flat commission, is exactly what procurement teams have been asking traditional agencies for and rarely getting.
There’s a cost pressure layer too. Creator fees have jumped sharply across tiers, with our coverage of creator fees climbing 200 percent showing agency margins getting squeezed from both directions: rising talent costs and brands demanding flatter fee structures. Holding companies that built their business on opaque markup percentages are structurally worse positioned to absorb that squeeze than lean creator shops that were never running on 15 percent commission math in the first place.
The Brand Side Calculus: Risk, ROI, and Operational Reality
For the marketer actually signing the contract, this fight isn’t about agency pride. It’s about three things: can I measure the return, can I control the risk, and can I move fast enough to matter.
- Measurement: Reach-based reporting is losing credibility fast. Our piece on measurement ditching reach for conversion proof reflects a broader shift that both holding companies and creator agencies are scrambling to accommodate. Whoever delivers cleaner attribution wins the next budget cycle, full stop.
- Risk: Brand safety, FTC disclosure compliance, and data handling still favor agencies with established legal and compliance infrastructure. This is WPP’s strongest remaining card.
- Speed: Creator agencies consistently outpace traditional shops on turnaround. If your campaign calendar is built around trend cycles rather than quarterly planning, that speed advantage is decisive.
Tools like those tracked by Sprout Social and benchmarking data from Statista increasingly show brands running hybrid models: holding company for compliance and large-scale media buying, creator agency for content velocity and cultural relevance. That hybrid approach isn’t a compromise. It’s quickly becoming the default operating model for any brand with a budget above seven figures.
Resources like HubSpot and professional networks like LinkedIn have both published guidance pushing marketers toward exactly this kind of blended vendor strategy, which tells you the pattern isn’t isolated to a few early adopters.
What This Means for Budget Allocation Next Year
Neither WPP nor Omnicom is going to disappear. They’re too embedded in global media buying infrastructure, and procurement teams still value a single point of contact for compliance and legal accountability. But the share of discretionary creative and content budget flowing to creator agencies is going to keep growing, and both holding companies know it.
The smarter move for brand marketers isn’t picking a side. It’s structuring contracts so you can shift spend between holding company and creator agency partners without renegotiating from scratch every quarter. That flexibility is worth more than loyalty to either camp right now.
FAQs
Frequently Asked Questions
Why are brands shifting budget away from traditional holding companies like WPP and Omnicom?
Brands are moving spend toward creator agencies because they typically deliver faster turnaround, lower production costs, and content that performs better on short-form platforms. Measurement tied to conversion rather than reach has also made it harder to justify legacy retainer models.
Is the Omnicom and Interpublic Group merger a direct response to creator agencies?
It’s one factor among several, but the timing and scale of the merger suggest Omnicom is trying to rebuild negotiating leverage and absorb smaller specialized agencies rather than compete with them head to head on speed.
Are holding companies still better for brand safety and compliance?
Generally, yes. Established agencies tend to have more mature legal, compliance, and disclosure infrastructure, which matters more as regulators like the FTC and ICO increase scrutiny of influencer disclosure and data practices.
Should brands pick one type of agency or run a hybrid model?
Most mid-to-large brands are landing on a hybrid approach: holding companies for large-scale media buying and compliance, creator agencies for content velocity and cultural relevance. This tends to outperform an exclusive relationship with either type of partner.
How should marketers structure contracts to stay flexible in this environment?
Build shorter contract terms, avoid exclusive retainers where possible, and insist on performance clauses tied to conversion metrics rather than reach or impressions. This protects your ability to reallocate budget as the competitive landscape keeps shifting.
The fight between Madison Avenue and creator agencies isn’t going to resolve with a clear winner. Build your vendor contracts for flexibility now, so you’re not stuck renegotiating when the next quarterly earnings call reshuffles the landscape again.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →