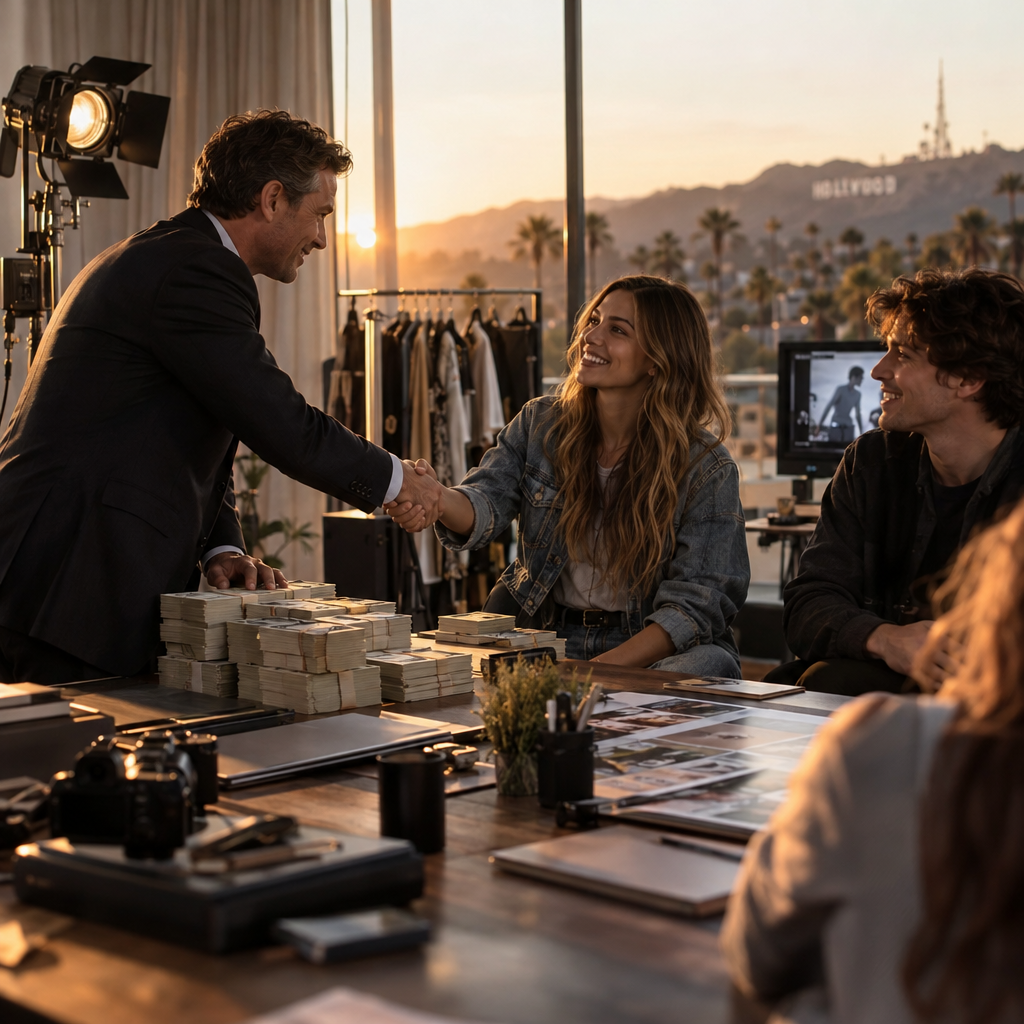
CAA now represents more YouTubers than some networks represent actors. That single fact should reorder how every brand marketer thinks about the creator middle class in 2026. Mid tier creators, the 50,000 to 500,000 follower cohort that brands used to treat as a bargain bin, are suddenly getting Hollywood style representation, production financing, and equity deals. The money flowing in isn’t influencer marketing money. It’s studio money. And it changes the economics of every campaign built around this tier.
The Money Behind the Shift
For years, the creator economy split cleanly into two tiers. Mega creators and celebrities got agency representation, brand licensing deals, and production budgets. Everyone else got a media kit and a DM negotiation. That gap is closing fast, and it’s closing because traditional entertainment capital finally figured out where the audience actually lives.
Talent agencies like CAA and WME have spent the past two years signing creators who, five years ago, wouldn’t have cleared the threshold for a junior agent’s attention. We covered this shift in depth when CAA and WME began signing creators at volume, and the pattern hasn’t slowed. What’s new in 2026 is the depth of the roster. Agencies aren’t just signing the creators with 10 million subscribers anymore. They’re building benches of mid tier talent, betting that institutional packaging (think development deals, brand licensing, merchandising infrastructure) turns a creator earning $150,000 a year into one earning seven figures within 24 months.
The creator middle class isn’t growing because more people are making content. It’s growing because institutional capital decided mid tier audiences are now worth underwriting.
Why Mid Tier Creators Are Suddenly Fundable
Here’s the uncomfortable truth for brands that built influencer programs around cheap mid tier access: the math that made this tier affordable is breaking down. Three forces are driving it.
- Retention over reach. Mid tier creators post more consistently and retain audience trust better than mega influencers, who increasingly feel like ad vehicles. Our recent data on creators choosing retainers over one offs shows this cohort wants stability, and institutional money is giving it to them.
- Platform economics favor depth. Algorithm changes across major platforms now reward sustained engagement over viral spikes, which is exactly what our analysis of recent algorithm updates found. Mid tier creators with loyal niche audiences are outperforming broad reach accounts on conversion.
- Studios need distribution, not just stars. Hollywood’s traditional distribution model is cracked. Streaming subscriber growth has flattened, and studios are using creator partnerships as a cheaper, faster way to reach audiences than traditional marketing. A mid tier creator with 200,000 highly engaged subscribers can outperform a six figure media buy.
Put those three together and you get a tier of creators that institutional capital views as undervalued assets. That’s not marketing language. That’s literally how agencies and production financiers are pricing this cohort now.
What “Institutional” Actually Means Here
Institutional doesn’t just mean an agent answering emails. It means production financing for original series, merchandising and licensing infrastructure, legal teams negotiating usage rights, and in some cases, equity stakes in media companies built around a creator’s IP. Compare that to the typical mid tier creator setup eighteen months ago: a part time manager, a rate card, and a Stripe account. The operational sophistication gap is closing, and brands negotiating directly with these creators are suddenly dealing with teams that understand leverage.
This mirrors a broader consolidation trend we’ve tracked across the agency landscape. Traditional holding companies have been scrambling as creator agencies steal budget share from legacy ad shops, and the roll up activity among creator focused agencies means brands now face fewer, bigger, better capitalized negotiating partners on the other side of the table.
What This Means for Brand Budgets
Let’s talk numbers, because that’s what actually changes behavior in a budget meeting. Mid tier creator fees have already climbed sharply across categories. Our reporting on creator fees climbing 200 percent and the parallel jump covered in fees rising 233 percent both point to the same structural shift. Institutional backing gives creators pricing power they didn’t have when they were negotiating solo.
Brands that built their influencer budgets around 2023 era rate cards are going to get a rude awakening in the next planning cycle. A mid tier creator who used to charge $3,000 for an integrated video might now come with an agency rate card starting at $12,000, bundled with usage rights, exclusivity clauses, and a minimum retainer commitment. That’s not price gouging. That’s what happens when representation enters a market that was previously unregulated and undervalued.
If your influencer budget model hasn’t been rebuilt in the last twelve months, it’s already pricing against a market that no longer exists.
This is the same dynamic we’ve seen play out at the nano and micro tiers, where fees have doubled on scarcity and micro influencer fees have tripled, forcing contract rebuilds across the board. The mid tier is simply the latest segment to get repriced, and arguably the one with the biggest budget exposure for brands because this is where most always on programs live.
Operational Risk: What Brands Need to Watch
Money brings sophistication, but it also brings complexity. Brands working with institutionally backed mid tier creators need to budget for more than higher fees. Expect longer contract negotiation cycles, stricter usage and exclusivity terms, and creators who are far less willing to do unpaid “exposure” collaborations. Agencies representing these creators are also vetting brand partners harder, which flips a dynamic marketers are used to. We’ve already seen this show up in how agency roll ups force brands to vet vendors more carefully, and the reverse is now also true: creators are vetting brands.
There’s also a measurement angle brands can’t ignore. As fees rise, finance teams will demand proof these partnerships convert, not just reach. The shift toward conversion focused measurement is already underway, and it becomes non negotiable once a creator relationship costs five figures a month instead of a few thousand dollars per post. If you can’t attribute revenue to a mid tier partnership, you won’t be able to justify the renewal when the agency comes back asking for 20 percent more next quarter.
Compliance teams should also pay attention. Institutionally backed creators tend to have cleaner disclosure practices because agencies don’t want FTC exposure, but the contracts themselves get more complex, with usage windows, whitelisting rights, and content ownership clauses that smaller legal teams on the brand side may not be equipped to negotiate. Review guidance from the Federal Trade Commission before finalizing any multi platform usage agreement, and loop in legal earlier than you think you need to.
How Should Brands Respond?
A few practical moves are worth making now, before the next budget cycle locks in.
- Re audit your creator roster by representation status. Flag which mid tier partners have signed with an agency in the past year. Their rate card is about to change, if it hasn’t already.
- Shift toward retainer models. Locking in multi month commitments now, before full institutional pricing hits, can protect budget against rapid fee escalation. This aligns with what we found in our coverage of always on pipelines cutting costs and improving retention.
- Build measurement infrastructure now. If you can’t prove ROI on a $3,000 mid tier partnership, you definitely won’t be able to prove it on a $15,000 one. Tools referenced by HubSpot and Sprout Social for attribution modeling are worth evaluating if your stack is thin here.
- Diversify tier exposure. Don’t let your entire creator budget concentrate in a mid tier segment that’s repricing fast. Spread risk across nano, micro, and mid tier to avoid getting squeezed in one bucket.
The Bigger Picture: Creators as Infrastructure
Zoom out and this trend fits a pattern we’ve been tracking for a while. Creators are no longer just rented media placements, they’re becoming owned infrastructure for both brands and now studios. Our piece on creators becoming owned infrastructure argued that the smartest brands are building long term, equity like relationships with creators rather than treating them as transactional ad inventory. Hollywood’s entry into the mid tier confirms that thesis. Studios aren’t buying ads from these creators, they’re investing in them as durable distribution channels.
For brand marketers, that’s actually useful framing. Stop thinking of mid tier creator budgets as a media line item and start thinking of them as talent investment, similar to how you’d evaluate a long term agency retainer or a flagship sponsorship. The pricing will feel uncomfortable in the short term. But the creators getting institutional backing are, by definition, the ones with the strongest retention, the cleanest brand safety records, and the most durable audiences. You’re not paying more for the same thing. You’re paying more for something that got structurally better.
Platforms are reinforcing this too. According to eMarketer, engagement quality metrics are increasingly weighted in platform algorithms, which benefits consistent mid tier creators over viral mega accounts. Reference data from Statista on creator economy valuation also shows the mid tier segment growing faster in revenue terms than either the top or bottom of the market over the past two years.
Takeaway
Treat your mid tier creator roster like an asset class that just got repriced by outside capital, not a line item you can negotiate down to last year’s rate. Audit representation status this quarter, lock in retainers where you can, and build the measurement case now so you’re not scrambling to justify spend when the next rate card lands.
FAQs
What counts as a mid tier creator in 2026?
Most brand teams define mid tier as creators with roughly 50,000 to 500,000 followers or subscribers on their primary platform, though engagement rate and niche authority matter more than raw follower count when agencies and studios evaluate deal value.
Why is Hollywood suddenly investing in mid tier creators?
Traditional studio distribution has slowed as streaming subscriber growth flattens, and mid tier creators offer cheaper, more trusted reach into engaged niche audiences than traditional media buys, making them attractive for production financing and brand licensing deals.
How much have mid tier creator fees increased?
Fee increases vary by category, but multiple reports across the creator economy point to increases ranging from 200 percent to over 230 percent for creators who have recently signed with talent agencies or management firms.
Should brands still work directly with mid tier creators, or go through agencies?
Direct relationships are still viable for creators without representation, but once a creator signs with an agency, brands should expect formal rate cards, usage rights negotiations, and less flexibility, so budgeting for agency involvement from the start avoids mid campaign surprises.
What’s the biggest risk for brands in this shift?
The biggest risk is budget misalignment: planning influencer spend against outdated rate expectations and getting caught without the measurement infrastructure to justify higher fees when finance teams ask for ROI proof.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →