Social commerce GMV growth is projected to outpace overall e-commerce expansion by a wide margin over the next several years, and most brand leaders still treat it like a side channel. That’s a budgeting mistake. Fashion already runs live shopping like a core revenue line. Electronics is quietly catching up. The question isn’t whether social checkout matters anymore. It’s whether your organization can prove it works before the next budget cycle.
The Numbers Behind Social Commerce GMV Growth
Global social commerce GMV has been climbing at rates that make traditional retail media look sluggish by comparison. Industry estimates from eMarketer and Statista consistently point to double-digit annual growth in social-driven transactions, with Asia-Pacific markets setting the pace and North America and Europe closing the gap through native checkout expansion on TikTok, Instagram, and Pinterest.
What changed? Platforms stopped treating commerce as a bolted-on feature and started building it into the core feed experience. TikTok Shop’s in-app checkout, Instagram’s product tagging overhaul, and Pinterest’s shoppable pins have collectively removed friction that used to kill conversion at the link-in-bio stage. Fewer taps, fewer drop-offs, more completed carts.
Brands that still measure social commerce as a top-of-funnel awareness play are leaving revenue on the table that competitors are already collecting.
That growth isn’t evenly distributed across categories, though. Fashion built the infrastructure first. Electronics is where the next wave of GMV is actually forming, and most brand teams haven’t noticed yet.
Fashion Leads, But Not Everywhere the Same Way
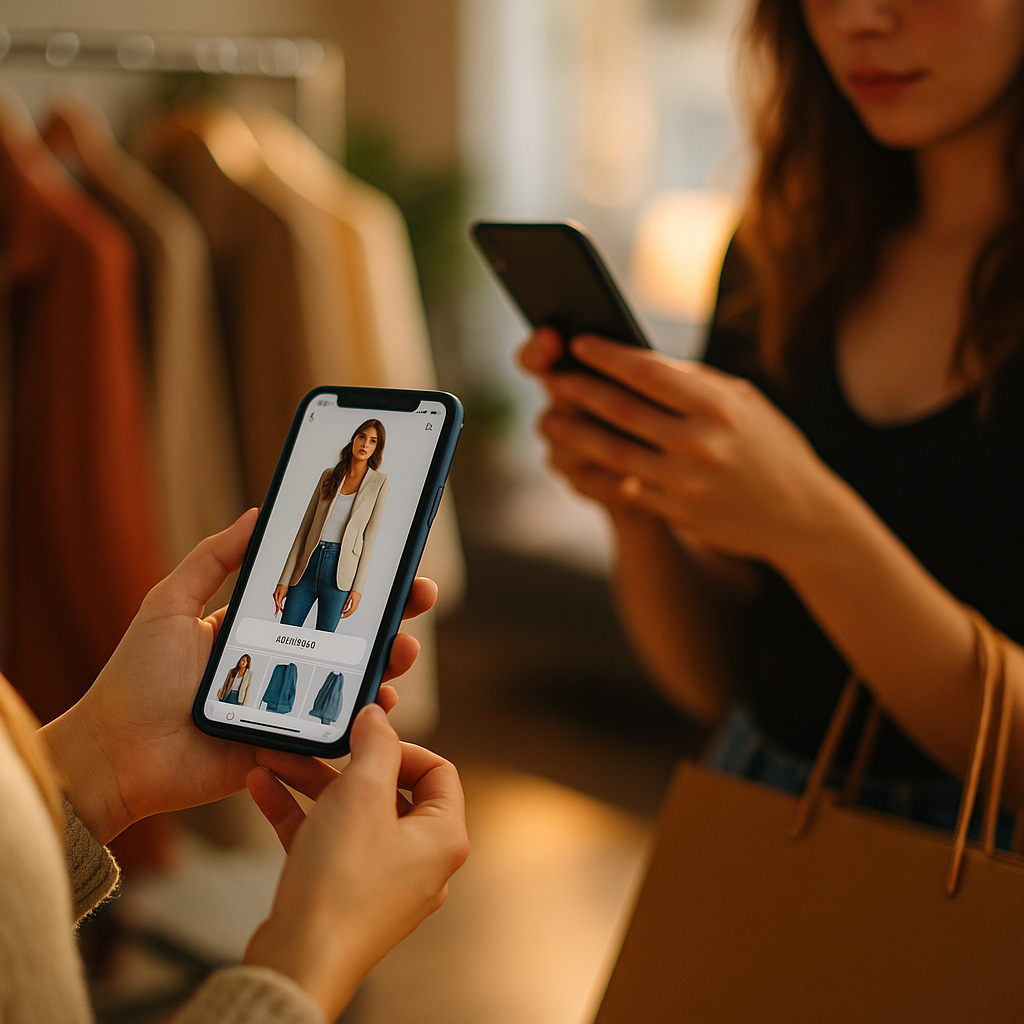
Fashion remains the anchor category for social commerce, and for obvious reasons: it’s visual, impulse-driven, and creators can demonstrate fit, styling, and texture in ways a product listing page never could. Live shopping events, haul videos, and try-on content convert at rates that outperform static product ads by a healthy margin.
But “fashion leads” hides a more nuanced story. Fast fashion and mid-tier apparel brands see the highest GMV velocity because price points sit below the psychological threshold where shoppers second-guess an impulse buy. Premium and luxury fashion brands see slower checkout conversion but higher average order value, and they’re using social commerce more for discovery and waitlist building than instant purchase.
This is where creator selection actually determines revenue outcomes, not just reach. A nano creator showing a $28 top converts differently than a mid-tier creator showcasing a $400 handbag. Brands that still cast primarily on follower count are missing this distinction entirely, which is a big part of why nano creator views now outperform raw follower count in reach-driven budget models.
- Fast fashion: high-frequency, low-AOV, algorithm-friendly content wins
- Mid-tier apparel: styling and UGC-style demos drive the bulk of conversions
- Luxury and premium: social functions more as a discovery layer feeding owned-channel purchase
Electronics Is the Sleeper Category
Electronics used to be a research-heavy, comparison-shopping category poorly suited to impulse-driven social feeds. That’s shifting fast. Unboxing content, spec breakdowns, and “is this worth it” review formats have found a home on TikTok and YouTube Shorts, and they’re converting at rates that surprised even the platforms tracking them.
Why the shift? Two reasons. First, creator-led review content solves the trust gap that used to require a trip to a retail store or a lengthy Amazon review scroll. Second, financing and bundle options integrated into social checkout have lowered the barrier for higher-ticket purchases. A $600 headphone set is a harder impulse buy than a $30 t-shirt, but a well-produced 45-second demo from a trusted tech creator, paired with a buy-now-pay-later option at checkout, closes more of that gap than brands expected.
Electronics brands are also benefiting from a data advantage fashion doesn’t always have: clearer purchase intent signals. Someone watching a laptop comparison video is further down the funnel than someone watching a fashion haul, which makes attribution modeling slightly more tractable, even if it’s still far from perfect.
This category shift is also reshaping who gets cast. Electronics brands increasingly need creators who can speak fluently about specs and comparisons, not just deliver polished production value, which lines up with the broader hiring trend where data fluency rivals video talent in creator-facing job postings.
Why Attribution Still Breaks the Business Case
Here’s the uncomfortable part. GMV growth numbers look great in an industry report, but most brand finance teams still can’t cleanly trace a social sale back to a specific creator, post, or campaign. The checkout journey fragments across platforms, and each one reports revenue differently, if it reports it at all.
TikTok Shop, Instagram Checkout, and YouTube’s shopping integrations each use their own attribution windows and reporting dashboards, which makes cross-platform GMV comparisons unreliable without a third-party layer stitching the data together. This is exactly the problem explored in depth around the checkout split forcing attribution fixes across major platforms.
Regulatory pressure is compounding this. The Federal Trade Commission continues to sharpen disclosure expectations for sponsored commerce content, which means brands need clean documentation not just for revenue proof but for compliance defense. If your influencer program can’t produce a clear paper trail from creator content to completed transaction, you’re exposed on two fronts simultaneously: unproven ROI and regulatory risk.
A GMV number without attribution is a marketing claim. A GMV number with attribution is a budget renewal.
Brands making real progress here are adopting standardized attribution frameworks rather than relying on platform-native reporting alone. The push toward the IAB attribution standard is one sign that the industry is finally trying to solve this at scale rather than platform by platform. Similarly, teams that have shifted to transaction-level attribution are seeing far more defensible ROAS conversations with finance leadership.
Platform Selection: Where Should Brands Place Bets?
Not every platform deserves equal budget weight, and category matters more than most media plans account for.
Fashion brands still get the highest GMV density from TikTok Shop, largely because the discovery algorithm rewards exactly the kind of visual, trend-responsive content fashion creators produce natively. Instagram remains strong for mid-funnel styling content and retargeting, but it converts fewer cold-traffic impulse buys than TikTok’s native checkout.
Electronics brands see a different mix. YouTube’s long-form review content still drives outsized influence on purchase decisions, even when the actual transaction happens elsewhere, which complicates last-click attribution but shouldn’t be ignored in budget allocation. Meta’s shopping ads perform well for retargeting warm audiences who’ve already watched a comparison video.
- TikTok Shop: strongest for fashion impulse purchases and trend-driven GMV spikes
- Instagram Checkout: strongest for mid-funnel styling and retargeting across both categories
- YouTube Shopping: strongest influence layer for electronics, weaker on direct last-click GMV
- Pinterest: underrated for fashion discovery with longer purchase cycles
Brands running multi-platform programs at scale often hit the same wall: legal, finance, and payment systems weren’t built for this volume of creator-driven transactions. That operational strain is well documented in coverage of how enterprise creator scaling cracks legal and payment systems, and it’s a warning worth heeding before you scale spend faster than your back-office can handle it.
Building the Internal Case for Budget
If you’re trying to move social commerce from experimental line item to protected budget category, the pitch needs three things finance actually cares about: comparable GMV benchmarks, clean attribution, and a documented compliance process.
Start by benchmarking your category against published GMV growth rates rather than generic “social commerce is booming” language. Fashion leadership can point to live shopping conversion data. Electronics teams should lean on the intent-signal advantage of review-driven content, since that’s the differentiator finance will find most credible.
Second, don’t present GMV in isolation. Pair it with a rebuilt ROAS model that reflects transaction-level data rather than platform-reported estimates, similar to the shift described in the ROAS mandate forcing brands to prove revenue. Finance teams have heard “trust the platform dashboard” too many times to accept it without a fight now.
Finally, get compliance documentation in order before you scale, not after. Payment delays and murky disclosure trails have already exposed brands to legal risk, a pattern examined in detail around creator payment delays and legal exposure. It’s far cheaper to build the process now than to clean it up after a regulatory inquiry.
FAQs
Frequently Asked Questions
What is driving social commerce GMV growth right now?
Native checkout integrations on TikTok, Instagram, and Pinterest have removed the friction that previously killed conversions at the link-in-bio stage, combined with creator-led content formats like live shopping and unboxing videos that build trust faster than static product pages.
Why does fashion still lead social commerce GMV?
Fashion products are highly visual and lend themselves to impulse buying, and creators can demonstrate fit, styling, and texture in ways that static listings cannot, which drives higher conversion rates for mid-tier and fast fashion price points specifically.
Is electronics a viable social commerce category for brands?
Yes. Creator-led review and unboxing content has closed the trust gap that used to require in-store research, and financing options integrated into social checkout have made higher-ticket electronics purchases more feasible directly through social platforms.
How should brands measure social commerce ROI accurately?
Brands need transaction-level attribution that goes beyond platform-native dashboards, ideally supported by a standardized framework, since cross-platform GMV comparisons are unreliable when each platform reports revenue differently.
What compliance risks come with social commerce growth?
Regulatory bodies like the FTC continue to sharpen disclosure requirements for sponsored commerce content, so brands scaling social checkout programs need documented creator agreements and clear disclosure practices to avoid legal exposure.
The brands winning social commerce right now aren’t the ones with the biggest GMV headlines. They’re the ones who can trace every dollar back to a specific creator, platform, and piece of content, then defend that number in a budget meeting without flinching.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →