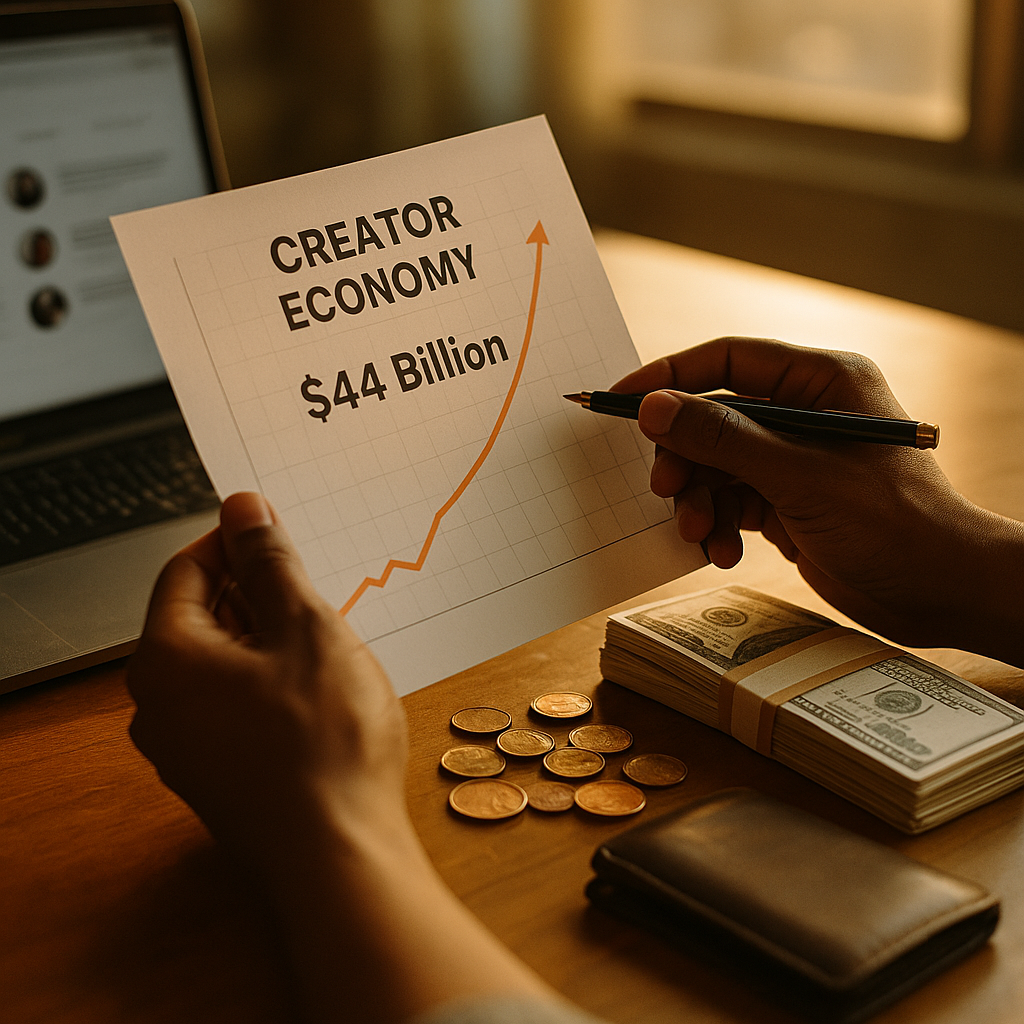
Forty four billion dollars. That is what brands now funnel into creator partnerships, and the number is not slowing down. If your 2026 media plan still treats influencer marketing as a test budget line item, you are already behind competitors who have rebuilt entire go-to-market strategies around it. The creator economy has stopped being an experiment. It is infrastructure.
The question is no longer whether to invest. It is where the dollars go, who controls them, and how brands prove the spend was worth it.
Why 44 Billion Dollars Is Just the Starting Line
The figure itself comes from aggregated spend across sponsored content, platform commerce, agency fees, and creator-owned media, and it reflects a market that has matured past its scrappy origins. According to eMarketer’s influencer marketing tracking, year over year growth has consistently outpaced traditional digital ad spend, and that gap is widening heading into next year. Our own reporting on the 44 billion dollar figure breaks down how fast that number moved from projection to reality.
What changed? Three things, really. CFOs stopped viewing creator spend as experimental and started treating it as a core media channel. Platforms built native commerce and attribution tools that make ROI easier to track (even if imperfectly). And brands realized that audiences trust a creator’s recommendation more than a banner ad, full stop.
Brands that still budget for influencer marketing as a discretionary add-on are competing against rivals who have folded it into core media planning, with the governance and measurement rigor that implies.
Where the Money Is Actually Moving
Growth is not evenly distributed. CPG brands are scaling fastest, but even there, maturity varies wildly by category, a gap our CPG spend benchmarks piece lays out in detail. Beauty and food brands are years ahead of categories like financial services or industrial B2B, which are only now building out creator programs.
Display and traditional programmatic budgets are shrinking to fund the shift. CFOs are not adding new money so much as rerouting it, a trend documented in our coverage of display budgets shrinking as creator line items grow. That reallocation matters for anyone building next year’s plan: the money has to come from somewhere, and it is coming from channels that used to be untouchable.
Agencies are racing to keep up. Holding companies like WPP and Omnicom are building dedicated creator teams, and Edelman’s aggressive hiring spree (covered in our piece on Edelman’s creator hiring push) signals that creator strategy is no longer a bolt-on service. It is a core offering brands expect from any agency partner.
Tiering Is Getting More Mathematical, Not Less
Budget allocation across creator tiers used to be gut instinct. Now it is closer to portfolio theory. Our analysis of creator tier ratios found that brands are deliberately balancing macro reach against micro trust, and the math behind those ratios is getting more rigorous every quarter.
Micro influencers continue to outperform macro accounts on engagement rate, a pattern that has held steady across multiple reporting cycles (see our breakdown of micro versus macro engagement data). Meanwhile, a glut of nano creators has handed brands unusual pricing leverage, something we unpacked in our piece on the nano influencer supply glut. If you are not renegotiating nano rates right now, you are leaving money on the table.
At the same time, some brands are moving in the opposite direction: consolidating rosters rather than expanding them. Our reporting on brands that halve creator rosters while betting on creative diversity shows a counterintuitive strategy gaining traction. Fewer creators, deeper relationships, more creative latitude. It is a bet that quality of partnership beats sheer volume.
The ROI Problem Nobody Has Fully Solved
Here is the uncomfortable truth hiding inside that 44 billion dollar figure: most brands still cannot prove their creator spend works. A widely cited industry survey found that 94 percent of marketers see gains from creator partnerships, yet 79 percent cannot actually prove it with hard data. We covered that gap directly in the creator ROI paradox, and it is arguably the single biggest risk hiding in 2026 budget plans.
Why does this keep happening? Partly because agencies oversell weak baselines. Our investigation into agency ROI claims and weak baselines found that many reported “lift” numbers compare against benchmarks that were never rigorous to begin with. Partly because the metrics themselves are shifting. Emotional resonance, brand lift, and sentiment are becoming as important as click through rate, a trend explored in our piece on emotional ROI as a measurement lens.
If your agency cannot show you the baseline it measured against, the “lift” they are reporting is a guess dressed up as a metric.
Twenty five creator economy experts recently went on record exposing exactly these unresolved measurement gaps in our feature on unresolved ROI problems. The consensus? Attribution tooling has improved, but it has not caught up to spend growth. That mismatch is precisely why conference agendas have shifted focus, something we documented in our coverage of how industry conferences are ditching reach metrics for attribution proof.
Compliance Risk Scales With the Budget
Bigger budgets mean bigger legal exposure. As creator marketplaces expand to accommodate demand, so does the compliance surface area brands have to manage. Our reporting on marketplace expansion and compliance risk flags disclosure failures, contract ambiguity, and platform policy drift as the three biggest exposure points for 2026.
Pay disputes are also rising. A recent industry survey found that roughly a quarter of marketers have had to navigate contract disagreements with creators, a trend covered in our piece on how pay terms and contracts are breaking down. If your legal team has not reviewed your standard creator agreement in the past twelve months, now is the time.
The FTC remains the most relevant regulatory body here, and its endorsement guidance continues to shape how disclosure requirements get enforced in the United States. Brands running international campaigns should also check guidance from the UK Information Commissioner’s Office, since data handling rules differ meaningfully across markets. New diligence tools are emerging to help here too. IMCX’s diligence rooms, covered in our piece on how they turn creator deals into audit trails, give brands a way to document compliance at the deal level rather than scrambling after the fact.
Format Shifts Are Reshaping Where Budgets Land
Live streaming commerce has hit 52.4 percent adoption among certain brand categories, forcing marketing teams to scramble on risk controls they were not prepared for. Our coverage of live streaming’s risk control gap is worth a read if your brand is considering QVC-style creator commerce.
Microdrama is another format brands cannot ignore. ALZA Festival’s debut signaled that episodic, short-form narrative content is ready for brand integration, something we unpacked in our piece on microdrama’s readiness for brand partnerships. Related to this, episodic creator series are consistently beating one-off posts on retention metrics, according to our analysis of episodic series performance data. If your content calendar is still built around single sponsored posts, you are optimizing for the wrong unit of measurement.
TikTok’s own forecasting ties emotional authenticity, what the platform calls “reali tea,” directly to budget allocation decisions. We covered this shift in our piece on TikTok’s emotional ROI forecast, and it reinforces a broader theme: platforms are actively shaping how brands measure success, not just where they spend.
Seeding Costs and the MarTech Squeeze
Product seeding used to be a rounding error. Not anymore. Seeding costs are increasingly getting absorbed into formal media budgets, raising scrutiny from finance teams who want to know why “free samples” now show up as six figure line items. Our piece on seeding costs shifting into media budgets covers this in detail.
On the tooling side, MarTech growth is topping 15 percent annually as creator management platforms absorb a growing share of budget, a trend we documented in our MarTech growth analysis. Agentic AI tools are part of this too. Adoption is growing nearly 20 percent, but brands are weighing real risk tradeoffs, something covered in our reporting on agentic marketing tool adoption. For a sense of where platforms like Meta’s business tools and TikTok’s ad platform are heading, watch how fast they integrate AI-driven creator matching, because that is where budget efficiency gains will come from next.
Pricing itself is getting more complicated. Our investigation into hidden cost drivers in influencer pricing found that usage rights, exclusivity clauses, and whitelisting fees often double the sticker price of a deal. Brands negotiating 2026 contracts should ask for itemized breakdowns before signing anything.
Deal flow itself is also relocating. IMCX’s return to LA, detailed in our coverage of creator deal hubs shifting west, and the platform’s structural changes rewarding contract terms over flat rates (see terms over rates deal structures) both suggest that where and how deals get negotiated is changing as fast as the dollar figures themselves.
Forecasting firm Technavio has mapped where creator budgets are headed next, and the Technavio budget forecast points to continued growth in commerce-integrated formats over pure awareness plays. That lines up with what we are seeing across the broader market, detailed further in our piece on how the 44 billion dollar economy is forcing budget rewrites industry wide.
What This Means for Your 2026 Plan
Pull these threads together and a clear picture emerges. The creator economy is no longer a channel you test. It is a budget category you govern, with the same rigor you’d apply to programmatic or paid search. That means clear measurement baselines, documented compliance processes, tiered creator strategy backed by actual data, and contracts that protect against the pay disputes and scope creep that are becoming more common as spend scales.
Tools like Sprout Social and HubSpot’s marketing resources can help operationalize some of this tracking, but software alone will not fix a measurement strategy built on weak baselines. That part is on your team.
Frequently Asked Questions
What does the 44 billion dollar creator economy figure actually include?
It aggregates sponsored content spend, creator-driven commerce, agency fees tied to influencer campaigns, and platform tools built specifically for creator partnerships. It does not include organic brand content with no paid creator involvement.
Is creator marketing spend replacing traditional digital advertising?
Partially. Many brands are rerouting budget from display and programmatic channels into creator partnerships rather than adding entirely new spend, which is why traditional display budgets have been shrinking as CFOs prioritize creator channels.
Why do most brands struggle to prove creator marketing ROI?
Weak measurement baselines are the main culprit. Many agencies report “lift” against benchmarks that were never rigorously established, and attribution tooling still lags behind the pace of spend growth across the industry.
Should brands prioritize macro or micro influencers for 2026 budgets?
Data consistently shows micro influencers outperform macro accounts on engagement rate, but most mature brands use a tiered mix: macro for reach, micro and nano for trust and conversion efficiency.
What compliance risks grow alongside creator budget increases?
Disclosure failures, contract ambiguity around usage rights, and pay disputes all scale with spend. Brands should review standard creator contracts annually and document compliance at the individual deal level.
Next step: Audit your current creator budget against actual measurement baselines this quarter, not next. If you cannot show the baseline your agency used to claim “lift,” renegotiate the reporting terms before you renew the contract.
Frequently Asked Questions
What does the 44 billion dollar creator economy figure actually include?
It aggregates sponsored content spend, creator-driven commerce, agency fees tied to influencer campaigns, and platform tools built specifically for creator partnerships. It does not include organic brand content with no paid creator involvement.
Is creator marketing spend replacing traditional digital advertising?
Partially. Many brands are rerouting budget from display and programmatic channels into creator partnerships rather than adding entirely new spend, which is why traditional display budgets have been shrinking as CFOs prioritize creator channels.
Why do most brands struggle to prove creator marketing ROI?
Weak measurement baselines are the main culprit. Many agencies report “lift” against benchmarks that were never rigorously established, and attribution tooling still lags behind the pace of spend growth across the industry.
Should brands prioritize macro or micro influencers for 2026 budgets?
Data consistently shows micro influencers outperform macro accounts on engagement rate, but most mature brands use a tiered mix: macro for reach, micro and nano for trust and conversion efficiency.
What compliance risks grow alongside creator budget increases?
Disclosure failures, contract ambiguity around usage rights, and pay disputes all scale with spend. Brands should review standard creator contracts annually and document compliance at the individual deal level.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →