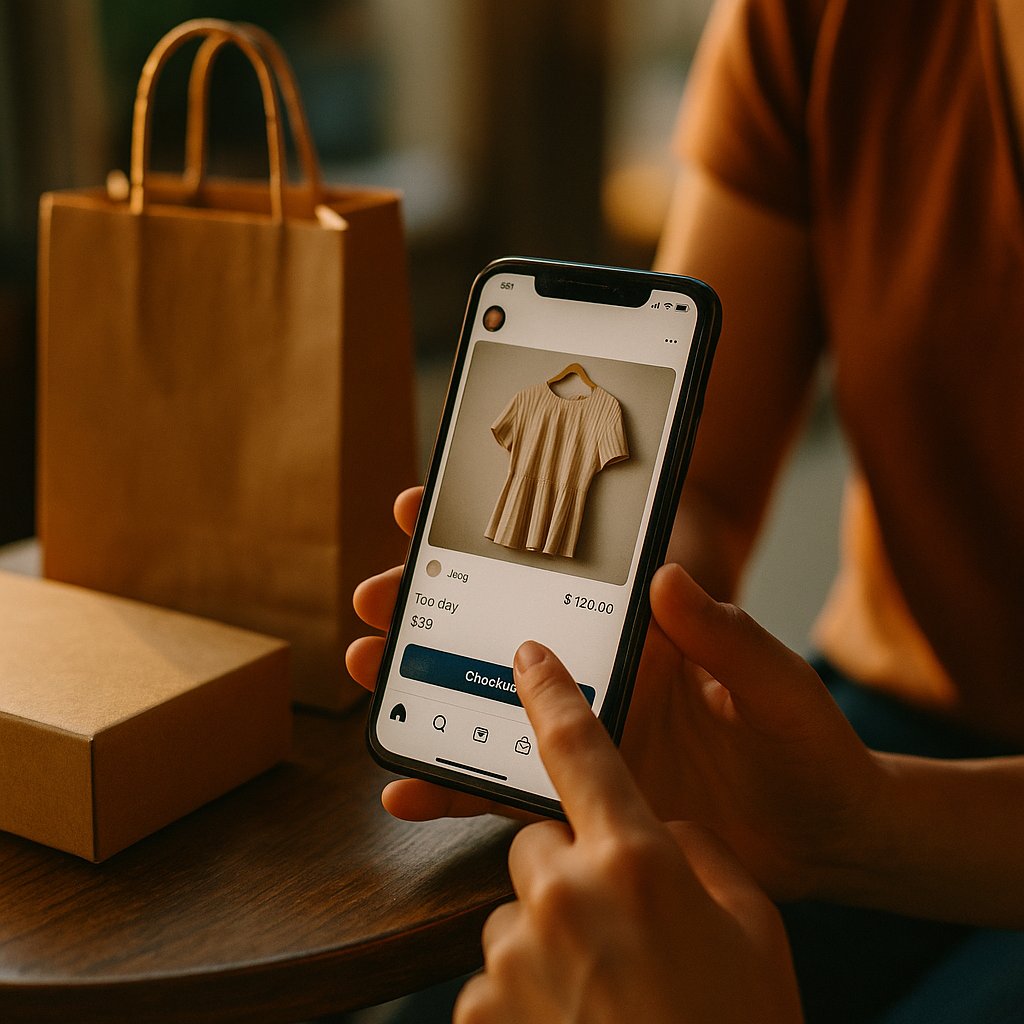
Fifty percent. That’s roughly the share of social media users who now say they’d complete a purchase without ever leaving the app, according to multiple platform-commissioned and independent surveys released over the past year. If you’re still routing every campaign click to an external landing page, you’re fighting the last war. The in feed checkout opportunity isn’t a future bet anymore. It’s a current-quarter budget line, and brands slow to size it correctly are handing conversion share to competitors who already rebuilt their funnel around native commerce.
Why “Buy In Feed” Suddenly Became the Default Expectation
Social commerce didn’t arrive overnight, but the tipping point is unmistakable. TikTok Shop, Instagram Checkout, Pinterest’s product pins, and YouTube’s shoppable ads have spent three years training users to expect a “buy now” button inside the same scroll where they discovered the product. That training worked. Friction is the enemy of impulse, and every extra tap between desire and purchase kills conversion rate.
Consider the trajectory: TikTok Shop alone hit 6.5 billion in gross merchandise value, a number that would have sounded implausible three years ago for a feature that barely existed. That’s not a niche behavior. That’s a mainstream shift in how commerce gets initiated, and brand teams that haven’t rebuilt their attribution models around it are underreporting their own social ROI.
If half your audience is willing to check out without leaving the feed, half your funnel is currently misconfigured if it still routes to an external site by default.
Sizing the Opportunity: What “Half” Actually Means for Budget
Let’s translate the headline stat into planning math, because “50% of users” is meaningless until you map it to your actual audience and average order value.
- Reach math: If your brand’s social audience across owned and paid channels is 2 million, roughly 1 million of those people are behaviorally primed to convert without leaving the app, assuming your category and price point fit impulse purchase norms.
- AOV compression: In feed checkout tends to favor lower-to-mid price points. Data from eMarketer and platform commerce reports consistently show higher conversion rates but smaller basket sizes compared to traditional ecommerce checkout flows.
- Attribution shift: Native checkout closes the loop platform-side, which means your last-click model in Google Analytics or a third-party MMM tool may be blind to a growing share of revenue unless you’re pulling platform-native sales data directly.
This is the uncomfortable part for finance-minded marketers: the opportunity is real, but it’s also partially invisible in legacy reporting. That’s exactly the kind of gap the CFO level audits now common in creator marketing are designed to catch.
The Creator Layer: Where In Feed Checkout Actually Converts
Native checkout doesn’t work in a vacuum. It works because creators build the trust that makes an impulse tap feel safe. Nano and micro creators, in particular, have shown outsized influence on in feed purchase decisions precisely because their audiences treat the recommendation as a friend’s word, not an ad. CreatorIQ data on nano creator ROI backs this up: smaller, higher-trust accounts are punching well above their follower count when the purchase path is one tap away.
Pair that with the engagement data from nano creator engagement benchmarks now topping 2.61%, and you get a clear operational takeaway: the creators best positioned to drive in feed checkout aren’t necessarily the ones with the biggest reach. They’re the ones whose audiences trust them enough to buy without leaving the conversation.
What’s Actually Blocking Adoption on the Brand Side
If half of users are ready to buy in feed, why isn’t every brand’s revenue mix already reflecting that? Three friction points keep showing up in agency and brand conversations.
- Inventory sync headaches. Native checkout requires real-time product feed integration with the platform. Brands running on legacy commerce stacks, or with fragmented SKU data across regions, often can’t guarantee accurate stock and pricing inside the app, which kills trust fast when a “buy” button leads to an out-of-stock error.
- Payment and tax complexity. Platform-native checkout means the platform, not your ecommerce provider, handles a chunk of the transaction. That raises legitimate questions about reconciliation, refund workflows, and sales tax compliance across jurisdictions.
- Fear of losing the customer relationship. When a sale happens entirely inside TikTok or Instagram, the brand often gets less first-party data than it would from a direct-to-site purchase. That’s a real tradeoff, and it deserves a deliberate answer rather than a default “opt out.”
None of these are dealbreakers. They’re operational problems with operational fixes, and the brands solving them now are the ones capturing share while competitors debate.
Compliance Doesn’t Disappear Just Because Checkout Got Easier
Easier checkout means faster transactions, which means less time for a shopper to notice a disclosure, a misleading claim, or an unvetted health or finance product. Regulators haven’t slowed down just because the buy button moved in feed. The FTC’s endorsement guidelines still apply in full to shoppable creator content, and platforms are increasingly building disclosure requirements directly into their commerce tools rather than leaving it to creator discretion.
This matters even more in regulated categories. The finance creator space has already had to adapt, as covered in our look at how finance creator deals now demand compliance proof. Expect similar scrutiny to extend to any category where in feed checkout removes the pause that used to happen between seeing a product and paying for it.
Frictionless checkout is a conversion win and a compliance risk in the same breath. Brands that treat it as only the former will eventually get a very expensive lesson in the latter.
Building the Operational Playbook
Sizing the opportunity is step one. Actually capturing it requires a few concrete moves that most brands haven’t fully executed yet.
- Audit your product feed for checkout readiness. Not every SKU belongs in native checkout. Start with your highest-velocity, lowest-complexity products, the ones with stable pricing, simple fulfillment, and minimal return complexity.
- Reconfigure attribution before you scale spend. Pull platform-native sales reporting into your dashboards alongside traditional web analytics. If you’re still measuring social’s contribution purely through referral traffic to your own site, you’re underselling the channel to your own leadership team.
- Match creator tier to checkout intent. High-trust, niche-aligned creators tend to drive better in feed conversion than broad-reach macro talent. This tracks with what we’ve seen in topical fit outperforming follower count across campaign performance data.
- Build a compliance checklist specific to shoppable content. Disclosure placement, pricing accuracy, and claims substantiation all need review before a creator’s shoppable video goes live, not after it’s already generating sales.
- Test before committing full catalog. Run a controlled pilot with a defined product set and a fixed measurement window before flipping native checkout on across your entire assortment.
Platforms are making this easier on their end too. Meta’s commerce tools and TikTok’s advertising platform both now offer catalog integration and native checkout options built specifically for brands making this transition, which lowers the technical lift considerably compared to two years ago.
Where This Fits in the Bigger Budget Conversation
In feed checkout doesn’t exist in isolation. It’s part of a broader reallocation of marketing budget toward creator-driven, platform-native commerce, a shift that’s already visible in the scale numbers coming out of the industry. The IAB’s 44 billion valuation of the creator ad market reflects exactly this kind of structural change, not a passing trend. Meanwhile, waste remains a persistent problem: the ANA’s finding that 29% of influencer spend goes wasted is a strong argument for tightening measurement precisely as checkout moves further in feed and further from traditional attribution tools.
The brands winning this transition aren’t necessarily spending more. They’re spending smarter, matching creator selection, product readiness, and compliance rigor to a checkout experience that rewards trust and punishes friction in equal measure. Tools like Sprout Social and HubSpot increasingly offer integrations that help bridge the reporting gap between native commerce and traditional CRM data, which is worth evaluating if your current stack still treats social as a top-of-funnel channel only.
Frequently Asked Questions
FAQs
What does “in feed checkout” actually mean for brands?
It means a consumer can complete a purchase entirely within a social app, without being redirected to a brand’s website. The transaction, payment, and often fulfillment handoff happen through the platform’s native commerce infrastructure.
Which platforms currently support native in feed checkout?
TikTok Shop, Instagram and Facebook Checkout through Meta’s commerce tools, and Pinterest’s shoppable pins all support some form of native purchase completion. YouTube has also expanded shoppable ad formats tied to product feeds.
Does in feed checkout hurt first-party data collection?
It can reduce direct data capture compared to a purchase made on a brand’s own site, since the platform handles the transaction. Brands should weigh this tradeoff against the conversion lift and consider hybrid approaches for higher-value products.
How should brands measure ROI on in feed checkout campaigns?
Combine platform-native sales reporting with traditional web analytics rather than relying on last-click attribution alone. Native checkout revenue often won’t appear in standard referral traffic reports, which understates the channel’s true contribution.
Are there compliance risks specific to shoppable creator content?
Yes. Disclosure requirements, pricing accuracy, and claims substantiation still apply under FTC endorsement guidelines regardless of how frictionless the checkout experience is. Faster purchase paths can mean less time for consumers to notice required disclosures, which increases scrutiny risk.
Next step: audit your top 20 SKUs for native checkout readiness this quarter, pair them with two or three high-trust creators already covered in your influencer roster, and run a 30-day pilot with platform-native sales tracking layered onto your existing dashboard before scaling spend further.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →