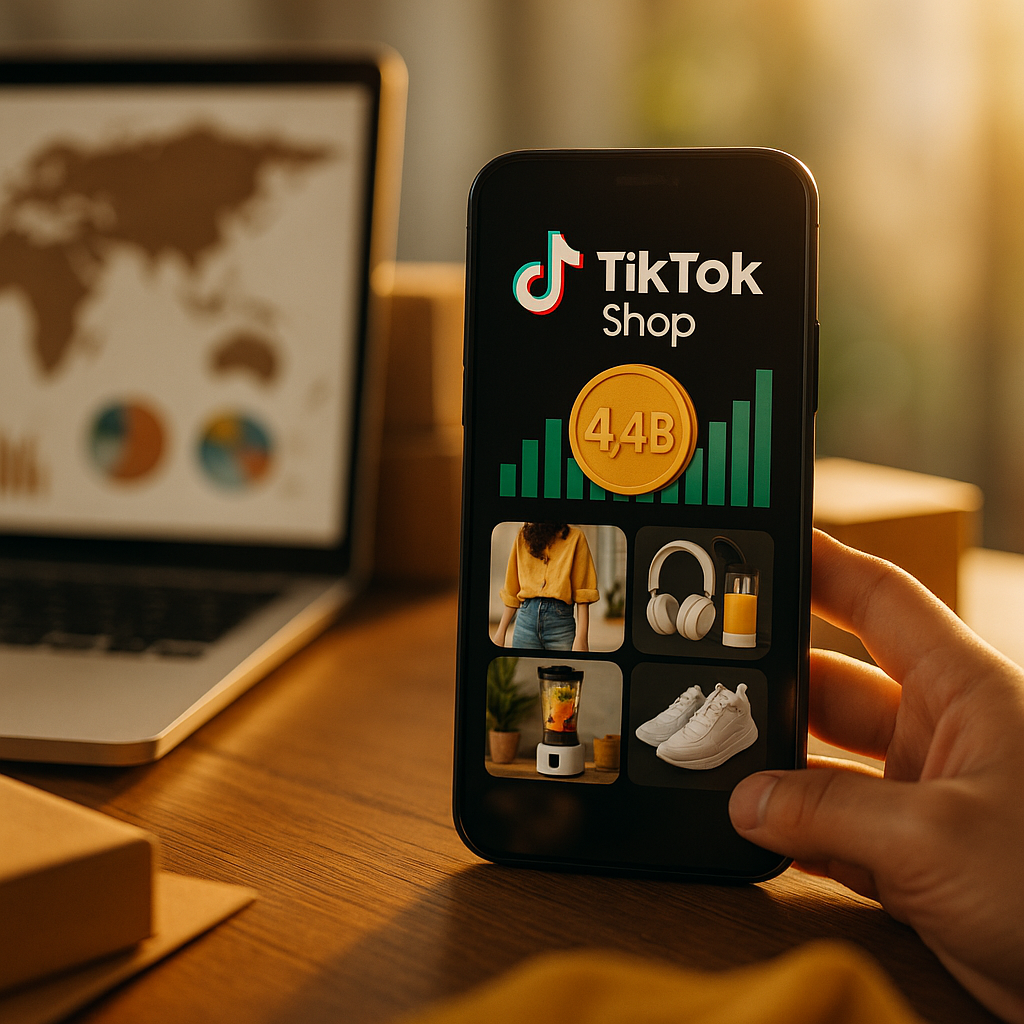
TikTok Shop crossed $4.4 billion in US sales, and most brands still don’t know which category shelf they should be fighting for. That number isn’t a vanity metric. It’s a map. And if you’re still treating TikTok Shop as a side experiment rather than a channel with category-specific economics, you’re leaving margin on the table.
This piece breaks down where that $4.4 billion actually came from, category by category, and what it means for brands deciding where to spend the next quarter’s influencer budget.
Why the Category Breakdown Matters More Than the Headline Number
Every platform milestone gets the same treatment: a big number, a press cycle, a few LinkedIn posts congratulating “the creator economy.” Then everyone moves on. That’s a mistake here. The $4.4 billion figure aggregates wildly different purchase behaviors across categories, and lumping them together hides the real signal.
Beauty buyers on TikTok Shop behave nothing like home goods buyers. Fashion impulse purchases convert on a completely different timeline than supplement subscriptions. If your team is building a single “TikTok Shop strategy” instead of category-specific playbooks, you’re already behind brands that have figured this out.
The brands winning on TikTok Shop aren’t the ones with the biggest budgets. They’re the ones who matched category behavior to creator tier and content format before their competitors did.
Beauty and Personal Care: The Category That Built the Platform
Beauty remains the single largest revenue driver inside TikTok Shop, and it’s not close. Skincare, color cosmetics, and haircare products convert at rates that make traditional DTC funnels look sluggish by comparison. The reason is structural: beauty content is inherently visual, demo-friendly, and impulse-driven. A fifteen-second before-and-after clip does more selling than a landing page ever could.
For brand entry planning, beauty is the most crowded lane but also the most proven. Expect higher creator rates and more competition for top-tier affiliate talent. This is exactly where nano and micro creators are quietly outperforming bigger names, a pattern documented in recent CreatorIQ data on nano creator ROI. If you’re entering beauty now, budget for volume across smaller creators rather than betting everything on a handful of mega-affiliates.
Fashion and Apparel: High Velocity, Thin Margins
Apparel sits close behind beauty in transaction volume, but margins tell a different story. Fast-fashion price points mean brands need high order volume to justify creator commissions, and returns eat into the math fast. Fit-check content, haul videos, and “get ready with me” formats dominate this category, and they age quickly. What sold last month won’t necessarily sell this month.
Brands entering apparel should treat TikTok Shop less like a stable retail channel and more like a fast-moving trend engine. That means shorter content cycles, faster creator turnaround, and less reliance on evergreen product listings.
Home, Kitchen, and the Rise of “Problem Solving” Content
Here’s where things get interesting for brands outside the obvious beauty and fashion lanes. Home and kitchen goods have grown faster than almost any other category on TikTok Shop, driven by a very specific content format: the “this actually works” demo. Think gadget reveals, cleaning hacks, and organizational products shot in a real kitchen, not a studio.
This category rewards authenticity over polish. A creator with 8,000 followers filming in their actual apartment often outsells a polished ad from a 500,000-follower lifestyle account. That’s consistent with broader engagement data showing smaller creators beating celebrity reach when relevance and trust are the deciding factors.
Brands entering home goods should prioritize product utility over aesthetic and lean into creators who genuinely use the product daily, not just campaign talent hired for a single post.
Electronics and Gadgets: Smaller Slice, Higher Ticket
Electronics haven’t captured the same share of total transactions as beauty or apparel, but average order values run higher, which matters when you’re modeling revenue per creator partnership. This category also skews toward longer consideration cycles. Buyers watch multiple reviews before purchasing, which means affiliate content needs staying power rather than a single viral moment.
If your brand sells anything in this space, plan for a slower ramp and a heavier reliance on searchable, evergreen content rather than trend-chasing formats.
Food, Beverage, and Supplements: Compliance Is the Real Entry Barrier
This category has grown fast, but it’s also the one most likely to trip up brands unfamiliar with disclosure and health-claim rules. Supplement and functional beverage brands are pouring budget into TikTok Shop, and regulators are paying attention. Any brand entering this space needs creator contracts that explicitly address claims language, not just posting cadence.
This is where the industry’s broader shift toward compliance-first creator programs becomes directly relevant. Finance and health-adjacent categories are already being scrutinized more heavily, a trend covered in depth in recent coverage of compliance demands in creator deals. Food and supplement brands should borrow that playbook rather than learning the hard way.
What This Means for Brand Entry Planning Right Now
So where should a brand actually start? The category data suggests a few clear moves.
- Beauty and personal care: Enter with a nano-heavy affiliate strategy, not a single flagship partnership.
- Fashion and apparel: Budget for speed. Content cycles are short and creator relationships need to be flexible.
- Home and kitchen: Prioritize authentic daily-use creators over polished production.
- Electronics: Expect slower conversion and invest in evergreen, review-style content.
- Food, beverage, and supplements: Lock down compliance language in contracts before scaling creator volume.
None of this works without the right deal structure, either. Brands still negotiating flat fees across every category are leaving performance upside on the table. The shift toward performance-based creator contracts is directly tied to categories like these, where conversion is trackable in real time through TikTok Shop’s own attribution.
TikTok Shop’s growth isn’t evenly distributed across categories, and treating it as one channel with one playbook is the fastest way to overspend and underperform.
The Bigger Trend Behind the Number
The $4.4 billion milestone also matters because of where the platform is headed next. TikTok Shop has since pushed past that figure, and coverage of the platform’s continued climb toward 6.5 billion dollars in sales confirms this isn’t a one-quarter spike. It’s a sustained shift in how consumers discover and purchase products, one that aligns with the broader pattern of shoppers completing purchases without ever leaving the app, as detailed in recent research on in-app purchase behavior.
For brands still running influencer programs that drive traffic off-platform to a separate checkout, this data should prompt a hard look at friction. Every extra click between discovery and purchase is a conversion you’re losing to a competitor already selling natively.
External benchmarking helps here too. eMarketer’s social commerce forecasts and Statista’s retail media data both point to the same trajectory: social platforms are becoming full-funnel retail environments, not just awareness channels. TikTok’s own advertising resources now reflect that shift, with shop-specific ad formats built around conversion rather than reach alone.
Where Brands Get This Wrong
The most common mistake isn’t picking the wrong category. It’s applying last year’s influencer strategy to a shop-first environment. Content built for awareness doesn’t automatically convert inside a shop feed. Creators who are great at brand storytelling aren’t always great at driving checkout, and vice versa. Brands need to audit their creator roster with that distinction in mind before allocating shop-specific budget.
It’s also worth checking internal capacity. Programs built for occasional campaign bursts often can’t handle the operational demands of continuous shop content, a gap explored in depth around the rise of creator operations roles outnumbering pure creative hires. If your team is still structured for quarterly campaigns, TikTok Shop’s always-on model will expose that gap fast.
For general best practices on structuring social commerce programs, HubSpot’s marketing resources and Sprout Social’s platform benchmarks offer useful operational frameworks worth cross-referencing against category-specific data.
Frequently Asked Questions
Which category drives the most TikTok Shop revenue?
Beauty and personal care remains the largest revenue category on TikTok Shop, driven by visual, demo-friendly content that converts quickly through affiliate creators.
Is TikTok Shop worth entering for a smaller brand?
Yes, particularly in categories like home goods and beauty where nano and micro creators consistently outperform larger accounts on conversion rate rather than raw reach.
What’s the biggest risk for food and supplement brands on TikTok Shop?
Compliance. Health and food claims made by affiliate creators can create regulatory exposure, so contracts need explicit disclosure and claims language before scaling.
How should brands allocate creator budget across categories?
Budget allocation should match category behavior: volume-based nano creator strategies for beauty and home goods, faster-turnaround content for apparel, and evergreen review content for electronics.
Does TikTok Shop replace the need for a separate DTC checkout?
Not entirely, but native in-app purchasing reduces friction significantly, and brands relying on off-platform checkout links are increasingly losing conversions to competitors selling directly in-feed.
Pick one category from this breakdown, audit your current creator mix against its specific conversion behavior, and reallocate budget before your competitors finish reading the same data.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →