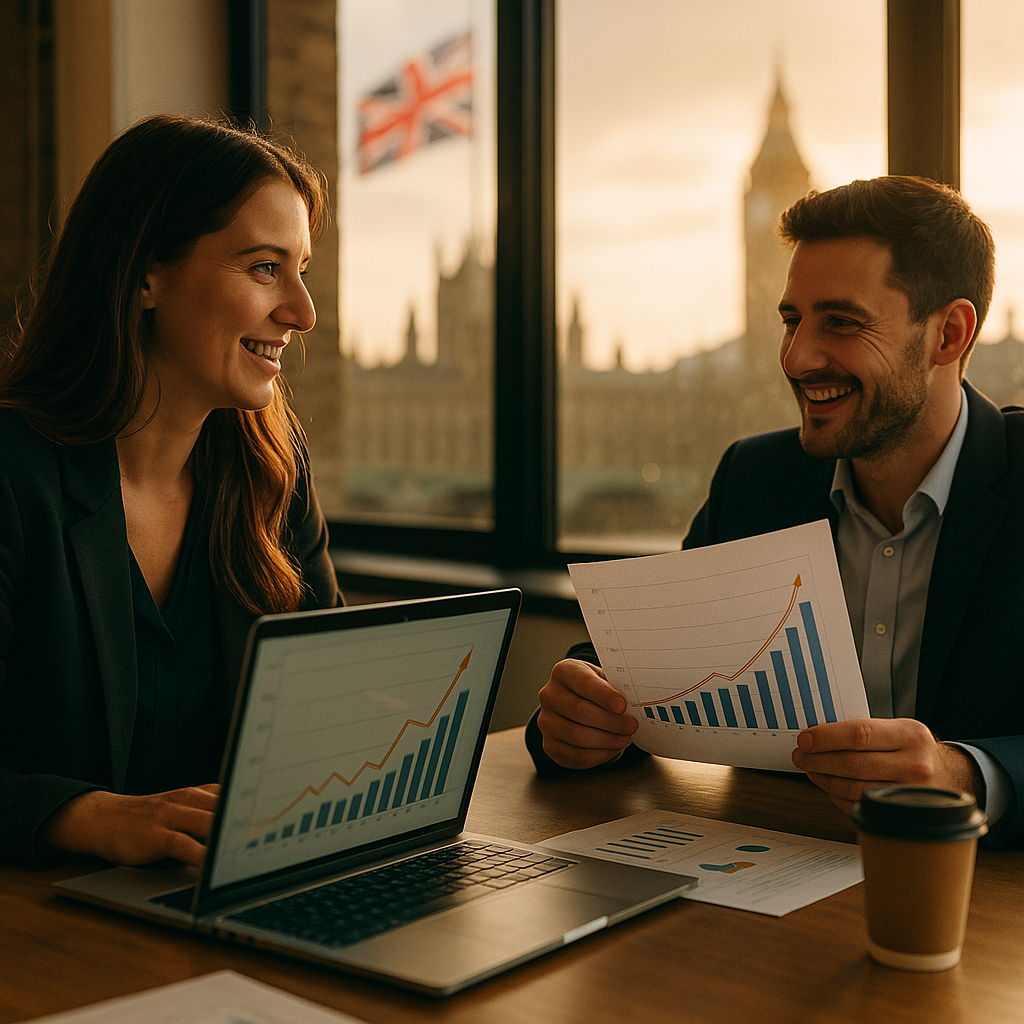
Nearly seven in ten UK marketers now call influencer marketing a core growth driver, not a side experiment. That puts the UK ahead of Germany, France, and the Nordics, where influencer budgets still sit closer to the “nice to have” column. Something structural has changed in how British brands think about creators, and it’s not just bigger budgets. It’s a shift in where influencer marketing sits on the org chart.
The Numbers Behind the Headline
Industry surveys circulating through late 2025 and into this year consistently put UK brands at or near the top of European rankings for influencer marketing maturity. Where continental peers still treat creator spend as a brand awareness line item, UK marketers increasingly tie it directly to revenue targets, customer acquisition cost, and even product development cycles.
That’s a meaningful jump from a few years ago, when influencer budgets were the first thing cut in a downturn. Now they’re one of the last. According to data referenced in 71 percent of brands plan creator budget increases again, UK retailers and D2C brands in particular are reallocating spend away from traditional display and paid social toward creator partnerships that can be tracked to conversion.
UK brands aren’t spending more on influencer marketing because it’s trendy. They’re spending more because finance teams can finally see where the money goes.
Why the UK Is Moving Faster Than the Rest of Europe
A few forces are converging here, and none of them are accidental.
- Attribution infrastructure matured first in the UK market. Retail media networks, affiliate tracking, and promo code systems rolled out earlier and more aggressively across British retailers than in most EU markets. See Promo Codes Still Drive 45.9 Percent of Attribution for how deeply that’s embedded now.
- Procurement got involved earlier. UK agencies and in-house teams moved influencer spend out of marketing’s discretionary pocket and into formal media budgets years before this became standard practice elsewhere, a trend tracked in Influencer Spend Reclassified as Media, Procurement Takes Over.
- Regulatory clarity reduced hesitation. The UK’s Advertising Standards Authority and the Information Commissioner’s Office have published relatively clear disclosure guidance, which gave brand legal teams confidence to scale programs instead of sitting on the sidelines worried about enforcement risk.
- English-language content travels. UK creators produce content that works across US, Australian, and broader English-speaking markets with minimal localization, stretching the ROI of every campaign dollar further than a similar spend in, say, Italy or Poland.
None of these factors alone would explain the gap. Together, they’ve built a market where influencer marketing behaves more like a measurable media channel and less like a reputational bet.
From Brand Lift to Bottom Line: The Mindset Shift
Ask a UK CMO in 2026 why they fund creator programs, and you’ll rarely hear “brand awareness” as the sole answer anymore. You’ll hear customer acquisition cost, repeat purchase rate, and incremental revenue per campaign.
That’s a direct consequence of better measurement tooling. Platforms that blend conversion data with creator performance have made it possible to defend influencer budgets the same way a performance marketer defends a Google Ads spend. The piece Conversion Blended Creator Plans Close the Influencer ROI Gap lays out exactly how this measurement shift happened, and UK brands were early adopters of the hybrid models it describes.
Still, not every objective is conversion-ready. Pure brand awareness campaigns remain notoriously hard to prove, and UK marketers haven’t solved that problem so much as they’ve learned to live with it by blending awareness plays with always-on conversion layers. For more on that tension, Awareness ROI Stays Unprovable While Conversion Tracking Wins is worth a read.
What Brands Are Actually Doing Differently
It’s not just sentiment surveys. Behavior on the ground backs this up.
UK agencies report that creator content is increasingly being lifted directly into paid media rotations rather than living only on organic creator channels. That shift, covered in Creator Content Turns Ad Creative, Retainers Lose Their Grip, means influencer output now does double duty: organic reach plus paid amplification, often funded from the same budget line that used to pay for a production agency shoot.
Brands are also casting smarter. Instead of chasing follower counts, UK marketing teams have leaned hard into persona-based matching, pairing creators to campaigns based on audience psychographics rather than raw reach. The approach detailed in Persona Matching Replaces Demographics in Creator Casting has become close to standard practice at mid-market and enterprise UK brands alike.
The brands calling influencer marketing a “core growth driver” aren’t the ones spending the most. They’re the ones who’ve stopped treating creator campaigns as a separate discipline from performance media.
Nano and Micro Creators Are Doing the Heavy Lifting
There’s also a supply-side story here. The UK creator pool at the nano and micro tier has exploded, giving brands far more granular targeting options than relying on a handful of macro names. That abundance has a downside, though: rates have flattened at the bottom of the market even as demand for genuinely scarce, high-performing creators keeps climbing. Nano Creator Glut Flattens Rates, Scarcity Still Wins ROI covers why volume alone no longer guarantees results, and why UK brands are getting pickier about who actually makes the cut.
Sourcing at this scale isn’t trivial either. Agencies managing hundreds of thousands of nano relationships are straining legacy workflows built for a world of a few dozen macro partnerships, a problem explored in 300,000 Nano Creators Break Agency Sourcing Playbooks.
Where the Risk Still Lives
None of this means UK brands have it all figured out. Growth confidence doesn’t erase operational risk, and a few cracks are worth watching.
- Fraud remains stubborn. Fake followers still account for the majority of detected influencer fraud cases, as outlined in Fake Followers Drive 56.5 Percent of Influencer Fraud. Scaling spend without scaling vetting is how brands end up paying for bot audiences.
- Disclosure pressure is rising. UK consumers are increasingly vocal about undisclosed partnerships, and regulators aren’t the only ones watching. Consumer sentiment data in 61 Percent Demand Disclosure, Unpaid Advocacy Faces Reckoning suggests brands that cut corners on compliance are gambling with trust they can’t easily rebuild.
- Trust itself is shifting away from influencers in some categories. Interestingly, frontline staff and employee voices are now outperforming influencers and even CEOs on certain trust metrics, per 46 Percent Trust Frontline Staff Over CEOs and Influencers. That’s a signal UK brands are starting to factor into channel mix decisions, especially in sectors like finance and healthcare.
Compliance isn’t just a legal checkbox either. The US Federal Trade Commission and UK’s ASA have both sharpened enforcement on disclosure in the past two years, and global brands running UK creators in US-facing campaigns need frameworks that satisfy both jurisdictions simultaneously.
What This Means for Budget Planning Going Forward
If you’re building a marketing budget for the year ahead, the UK data offers a fairly clear playbook: treat influencer spend as media, not PR. That means demanding the same attribution rigor you’d apply to paid search, building fraud detection into your vetting process rather than bolting it on after a campaign underperforms, and resisting the temptation to chase reach over relevance.
Tools referenced across recent industry coverage, including platforms tracked by eMarketer and benchmarking data from Statista, consistently show that brands blending creator content with retail media and CTV buys see stronger incremental lift than those running influencer campaigns in isolation. That convergence trend is picked apart in CTV Ad Spend Merges With Creator Budgets, Attribution Lags, and it’s a model UK brands are already testing at scale.
Platforms matter too. LinkedIn has quietly overtaken Instagram for engagement in certain B2B-adjacent sectors like retail and hospitality recruitment marketing, a shift worth understanding before you default to the usual channel mix. Details are in LinkedIn Overtakes Instagram in Retail and Hospitality Engagement.
Frequently Asked Questions
FAQs
Why do UK brands rate influencer marketing higher than other European markets?
UK brands benefit from more mature attribution infrastructure, earlier procurement involvement in creator budgets, clearer regulatory guidance from the ASA and ICO, and content that travels well across English-speaking markets without heavy localization.
Is influencer marketing replacing traditional advertising budgets in the UK?
Not entirely, but it’s absorbing a growing share. Many UK brands now fold creator content directly into paid media rotations, which blurs the line between organic influencer work and traditional ad spend rather than replacing one with the other.
What risks should brands watch when scaling influencer programs quickly?
Influencer fraud, particularly fake follower schemes, remains a significant issue. Disclosure compliance is another growing pressure point, as consumers and regulators both scrutinize undisclosed partnerships more closely than they did a few years ago.
How are UK brands measuring influencer marketing ROI?
Most are blending conversion tracking, such as promo codes and affiliate links, with broader brand lift studies. Pure awareness campaigns are still hard to attribute precisely, so many brands pair them with always-on conversion-focused creator activity.
Should smaller brands outside the UK follow this playbook?
The core principles, treating influencer spend as measurable media, vetting for fraud, and prioritizing audience relevance over raw reach, apply regardless of market. Smaller brands just need to scale the infrastructure to their budget rather than copying enterprise-level tooling outright.
The takeaway for marketing leaders outside the UK is simple: stop waiting for influencer marketing to “prove itself” as a separate category. Fold it into your media measurement stack now, build fraud and disclosure checks into vetting from day one, and benchmark against the UK’s conversion-first approach before your next budget cycle locks in.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →