

Fifty two percent. That’s the share of online shoppers in key markets who now say they’ve made a purchase directly through a livestream, according to recent industry tracking. When more than half your addressable audience is already buying this way, “experimental channel” stops being an accurate label. Live commerce is becoming the primary channel for a growing slice of categories, and the brands still treating it as a side bet are going to spend the next eighteen months playing catch up.
This isn’t a prediction dressed up as inevitability. It’s a math problem. Streaming adoption curves rarely plateau quietly once they cross the halfway mark, they tend to accelerate as infrastructure, creator supply, and platform incentives align. The question for brand leaders isn’t whether live commerce matters. It’s whether your org chart, budget lines, and compliance playbook will be ready when it’s the default, not the exception.
The Numbers Behind the Shift
The 52 percent figure didn’t appear overnight. We covered the moment live commerce crossed the 50 percent threshold, and the climb since then has been steady rather than explosive, which is arguably more telling. Slow, sustained growth usually signals structural change rather than a hype cycle. Platforms like TikTok Shop, Amazon Live, and regional players in Southeast Asia have spent years building the logistics, payment rails, and creator incentive structures that make streaming checkout frictionless. That groundwork is why adoption didn’t stall at a novelty ceiling.
Analysts at eMarketer and Statista have both flagged social and live commerce as the fastest growing subset of ecommerce spend, outpacing traditional online retail growth by a wide margin in multiple recent forecasts. Pair that with the broader shift we detailed in social commerce hitting trillion dollar pace, and the pattern is clear: transactional content is absorbing budget that used to sit in static display and even traditional influencer gifting.
When live commerce crosses the halfway mark of buyer behavior, it stops being a channel you test and becomes infrastructure you build around.
Why 2027 Is the Planning Deadline, Not the Finish Line
Set your planning horizon at the point where live commerce becomes the dominant discovery and purchase path in your category, not just a growing one. For many verticals, especially beauty, fashion, and consumer electronics, that point arrives faster than most five year roadmaps assume. Budget cycles move in annual increments. Platform capability moves in quarterly releases. If your 2027 media plan still treats livestream as a line item under “emerging formats,” you’re planning for a channel that will already be mature by the time the plan goes live.
Here’s the uncomfortable part: building live commerce capability isn’t a checkbox. It requires studio infrastructure, trained on-camera talent (creator or internal), real-time inventory syncing, and a customer service layer that can handle live Q&A at scale. None of that gets built in a single budget cycle. Brands that start now get a two to three year head start on the operational muscle memory that separates a polished livestream from an amateur one that tanks conversion.
What a Realistic Planning Window Looks Like
- Short term (next two quarters): pilot formats, test creator pairings, validate platform checkout flows.
- Mid term (next twelve months): build repeatable production workflows, train internal hosts, negotiate creator retainers instead of one off deals.
- Long term (eighteen to thirty six months): treat live commerce as a standing channel with its own P&L, not a campaign tactic.
What Actually Changes When Streaming Becomes the Default
Moving from occasional livestream events to a primary channel reshapes more than the media plan. It touches merchandising, customer service, and even how you measure success. GMV, not reach, becomes the headline metric, a shift we’ve already tracked across the broader creator commerce space in GMV overtaking reach as the scorecard standard. Reach told you who saw a post. GMV tells you who bought something, in real time, during a live session you can measure to the minute.
That metric shift forces a scheduling shift too. Live commerce rewards frequency and consistency the same way search rewards fresh content. A single quarterly flagship stream won’t move the needle the way a weekly cadence does, because algorithmic distribution on most platforms favors creators and brands who show up reliably. That’s an operational commitment, not a marketing campaign.
It also changes who’s in the room when campaigns get greenlit. Production teams, legal, and customer service need a seat at the table earlier, because live selling compresses the usual review cycle into minutes instead of weeks. We’ve written about how this operational pressure is already forcing brands to build dedicated ops stacks in our coverage of the 52 percent milestone, and the pattern holds: the brands winning here aren’t the ones with the biggest budgets, they’re the ones with the tightest internal coordination.
Platform Selection: Where the Volume Actually Lives
Not every platform deserves equal investment. TikTok Shop has pulled ahead in volume for impulse categories like beauty and apparel, while Amazon Live continues to dominate for considered purchases where buyers already trust the checkout experience. Instagram and YouTube are playing catch up on native checkout but still win on discovery for higher ticket items. Check current ad and commerce specs directly through TikTok’s advertising resources and Meta’s business platform before committing budget, because feature rollouts shift quarterly and regional availability varies more than most media plans account for.
The mistake we see most often: brands spreading thin across four platforms instead of going deep on one or two where their audience actually transacts. Live commerce rewards depth. A host who’s streamed two hundred times on one platform converts better than one who’s streamed fifty times each across four. Pick your primary platform based on where your category’s purchase intent already concentrates, then expand only once that channel is profitable on its own.
The Compliance Gap Nobody Budgeted For
Here’s where live commerce gets genuinely risky. Real-time claims made during a livestream, about pricing, product efficacy, or availability, are much harder to review and correct than static ad copy. A host overstating a health benefit or misquoting a discount isn’t a typo you fix in an edit. It’s a live transaction record. Regulatory bodies are paying attention: the FTC has already signaled increased scrutiny of endorsement disclosures in dynamic and live formats, and brands operating across borders need to track equivalent guidance from bodies like the ICO in the UK.
We’ve covered this tension in depth in creator commerce outpacing compliance, and the gap hasn’t closed. Most brands still rely on pre-stream briefing documents and hope the host sticks to the script. That’s not a compliance program, that’s a prayer.
A livestream claim is a live transaction record. Treat your host briefing like a legal document, not a vibe check.
What works instead: build a real-time moderation layer with a designated compliance reviewer monitoring the stream, pre-approved claim language for every product featured, and a documented correction protocol if a host misspeaks. Platforms like Sprout Social and similar social management tools are adding live monitoring features specifically for this use case. Build this now, while stream volume is manageable, not after a regulatory complaint forces the issue.
Budget Reallocation: Where the Money Should Move
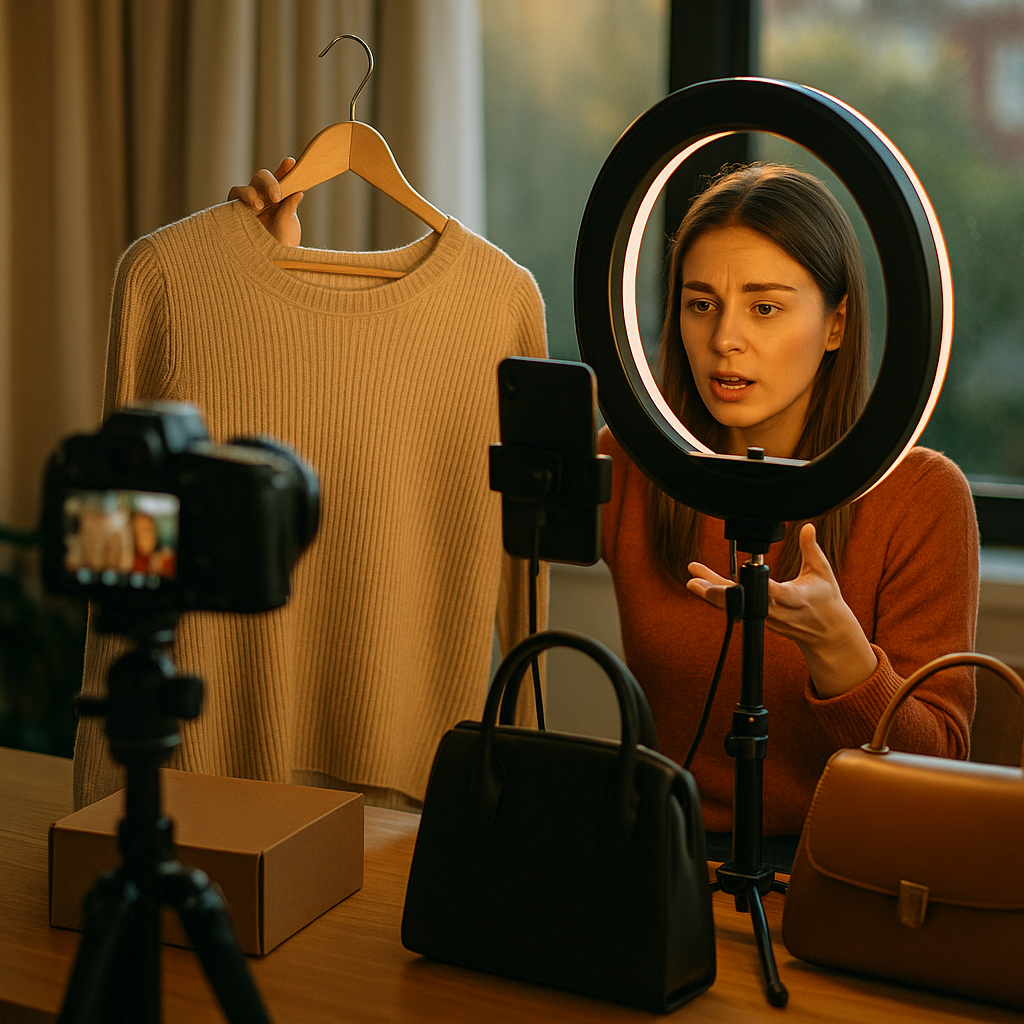
If live commerce is heading toward primary channel status, budget needs to move ahead of the curve, not behind it. That typically means pulling spend from one-off influencer gifting campaigns and static UGC production, and redirecting it toward retainer-based creator partnerships who can host consistently. It also means investing in production quality: lighting, audio, and a reliable streaming setup pay for themselves in conversion lift within a few sessions.
Consider equity or revenue-share arrangements with top-performing hosts, a model we explored in brands trading flat fees for equity. When a creator’s livestream performance directly drives GMV, aligning their incentive with revenue rather than a flat appearance fee tends to produce stronger, more consistent results.
For deeper context on how creator economics are shifting more broadly, our analysis of the creator economy hitting 44 billion lays out where budget lines are moving across the board, live commerce included.
FAQs
Visible FAQ content below.
Frequently Asked Questions
What does it mean for live commerce to become a primary channel?
It means live streaming shifts from a supplemental tactic to the main path customers use to discover and purchase products in a given category, requiring dedicated budget, staffing, and infrastructure rather than occasional campaign support.
Why is 2027 cited as a planning target for live commerce?
Adoption trends suggest live commerce will reach dominant market share in several consumer categories by that point, and the operational infrastructure needed to compete, production, staffing, compliance, takes longer to build than most annual budget cycles allow.
Which platforms should brands prioritize for live commerce?
Platform choice depends on category. TikTok Shop tends to lead for impulse purchase categories, Amazon Live performs well for considered purchases, and Instagram or YouTube still win on discovery for higher ticket items. Brands should concentrate investment where their audience already transacts rather than spreading thin.
What compliance risks are unique to live commerce?
Real-time claims made during a livestream are harder to correct than static ad copy, creating exposure around pricing accuracy, endorsement disclosure, and product claims. Brands need real-time moderation and pre-approved claim language rather than relying on host briefings alone.
How should brands measure live commerce success?
GMV generated during live sessions is the primary metric, supplemented by conversion rate, average order value, and repeat viewer rate. Reach and follower counts are poor predictors of live commerce performance.
Next step: Audit your current livestream cadence this quarter. If you’re not streaming weekly on at least one platform with a documented compliance review process, you’re not building toward a primary channel, you’re still running a pilot.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst

-
2

The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3

Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4

Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5

The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6

NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7

Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8

Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →