Nielsen puts streaming’s share of total TV viewing above 44% heading into 2026, and the remote control has quietly become a shopping cart. Living room commerce is no longer a future-state slide in a pitch deck. It’s the reason your CTV budget and your creator budget are about to merge into one line item, whether your org chart is ready for it or not.
The Big Screen Stopped Being Passive
For years, CTV was treated like digital billboard space: big reach, weak attribution, mostly a brand-awareness play. Creator content, meanwhile, lived on phones, optimized for swipe-speed and comment sections. Those two worlds rarely touched.
That separation is collapsing fast. YouTube’s CTV ad revenue crossed $1.1 billion in a single quarter, and a meaningful chunk of that spend is now running against creator-made content rather than traditional broadcast-style ads, as we covered in our breakdown of how YouTube CTV ad revenue resets creator briefs. Roku, Amazon Fire TV, and Samsung TV Plus have all layered shoppable overlays and QR-triggered checkout onto content that, a few years ago, would have been strictly a mobile-first format.
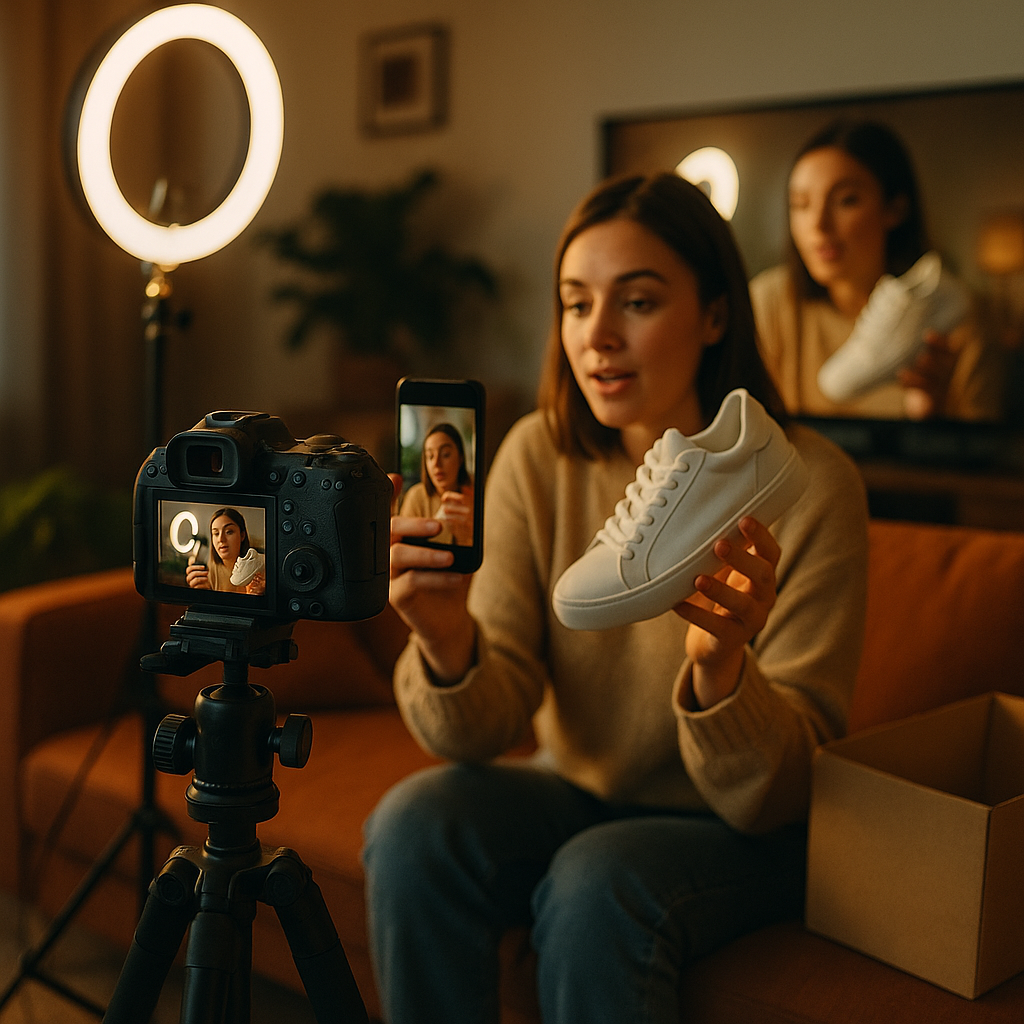
The practical result: a creator’s product review, originally shot for a vertical phone screen, now plays on a 65-inch TV with a “shop this look” prompt hovering in the corner. That’s a fundamentally different creative and measurement problem than either channel solved on its own.
The living room is becoming the last mile of the funnel, not the top of it, and most brand measurement stacks still aren’t built to track a purchase that started with a creator video and finished on a connected TV remote.
Why Brands Can’t Treat CTV and Creator Budgets Separately Anymore
Ask most CMOs where their CTV dollars live and where their creator dollars live, and you’ll get two different answers, two different agencies, and two different reporting dashboards. That’s the operational drag point in 2026.
The convergence isn’t just about format. It’s about attribution logic. A viewer might discover a product via a TikTok creator, watch a longer-form review on YouTube’s living room app, then complete the purchase through a retail media network. Trying to credit that journey with siloed CTV and social reporting produces garbage data, the kind that fuels arguments in budget meetings rather than resolving them.
Brands that have moved fastest here are the ones already treating influencer spend as a performance channel, not a brand-lift experiment. Our look at the 4 Rs framework replacing vanity metrics is directly relevant: reach, resonance, retention, and revenue all get harder to track once a single asset lives across a phone screen and a TV screen simultaneously. If your measurement stack can’t unify those signals, you’re flying blind on half your funnel.
What This Means for Creator Casting
Casting for living room commerce is not the same as casting for a Reels campaign. A creator who crushes it in a 15-second vertical clip might fall flat when their content plays at TV scale, where pacing, audio quality, and production polish get scrutinized differently. Some brands are responding by bringing casting decisions in-house so they can test creators across formats faster, a shift we detailed in Coty’s move to bring creator casting in house. Waiting on agency turnaround times doesn’t work when you need to know within days whether a creator’s content holds up on a 4K screen.
Brief-writing has to change too. D2C teams already rewriting briefs to chase purchase intent, as covered in our piece on D2C brands rewriting creator briefs, now need a second layer: shot composition and pacing notes for dual-format delivery. That’s more production overhead, but it’s cheaper than shooting two separate campaigns.
Live Shopping Finds a New Home
Live shopping has been treated as a mobile-and-app phenomenon, largely because that’s where TikTok Shop and Amazon Live built their early traction. But connected TV is starting to host live shoppable events too, particularly around retail moments like back-to-school and holiday drops.
Growth in live shopping formats is already forcing brands to rethink their video budget splits, a trend we broke down in our analysis of the live shopping growth rate reshaping video budgets. Add a CTV distribution layer to that, and you get creators hosting live shopping segments that stream simultaneously to phones and televisions, with checkout links that adapt to the device. That’s not a hypothetical. Amazon has piloted exactly this with Fire TV integrations, and Walmart’s connected TV ad unit has tested similar shoppable video formats.
The operational catch is inventory and fulfillment syncing across two very different purchase paths (remote-based checkout on TV versus tap-to-buy on mobile). Brands that haven’t stress-tested this dual pathway are going to find out the hard way during a high-traffic live event.
Affiliate Attribution Gets Harder, Then Gets Better
Affiliate-driven influencer deals have been climbing steadily, with affiliate spend up sharply as attribution models mature, per our coverage of affiliate spend jumping as attribution matures. The living room adds a wrinkle: unique codes and trackable links work cleanly on mobile, but CTV environments often strip out the granular click-level data brands rely on.
Some networks are solving this with device-graph matching, connecting a household’s TV viewing to its mobile and desktop purchase behavior through shared identifiers. It’s imperfect, and privacy-conscious marketers should treat these solutions with appropriate scrutiny given ongoing shifts in consent requirements, similar to what we covered in privacy-first personalization rebuilding data consent. But the direction is clear: attribution across screens is becoming table stakes, not a nice-to-have.
Trust Still Does the Heavy Lifting
None of this matters if the underlying trust equation doesn’t hold. Shoppers already report trusting creators roughly 2.4 times more than traditional brand advertising, according to our reporting on how shoppers trust creators 2.4x more. Moving that trusted content onto a bigger screen, in a more “advertising-coded” environment like a TV, is a risk. Viewers who tune out traditional TV ads may apply the same skepticism to creator content once it looks and feels like a commercial.
The brands navigating this well are keeping the creator’s authentic voice intact rather than reformatting content into slick TV-spot production values. Polish kills the thing that made the content work in the first place. If it stops feeling like a recommendation and starts feeling like an ad, the trust premium disappears, and so does the conversion lift.
Where AI Fits Into the Living Room Equation
AI martech spend is tripling, and a chunk of that investment is going toward format-adaptation tools, systems that can automatically resize, repace, and recompose creator content for different screen environments without a full reshoot. Our coverage of the AI martech market forcing creator budget reshuffles is a useful reference point for where this spend is headed.
This matters enormously for living room commerce because reshooting every asset for TV-native pacing is expensive and slow. AI-assisted repurposing lets a single creator shoot once and distribute across mobile, CTV, and even digital out-of-home with minimal manual editing. It’s not perfect yet, output still needs human review for pacing and brand safety, but it’s closing the gap between mobile-native content and TV-ready content faster than most measurement and legal teams can keep up with.
Worth noting: platforms are also facing new algorithm transparency requirements that affect how creator content gets distributed and ranked, a shift covered in our piece on algorithm transparency rules reshaping ad budgets. As CTV apps adopt similar recommendation engines to social platforms, those transparency questions will follow the content into the living room too.
Building the Internal Muscle
Most marketing orgs still have separate reporting lines for linear/CTV media buying and influencer marketing. That structure made sense when the two channels didn’t overlap. It doesn’t make sense anymore.
Companies that have created dedicated creator partnership roles, treating the function as retention infrastructure rather than a campaign-by-campaign hire, as detailed in our piece on creator partnership hires signaling retention infrastructure, are better positioned to own this convergence. The job titles showing up in job postings increasingly reflect this blended skill set: media buying literacy plus creator relationship management plus performance measurement, all in one role. That’s a hard hire, but it’s the hire that’s coming.
For benchmarking, industry data from eMarketer and Statista on connected TV ad spend growth gives finance teams the third-party validation they need to justify reallocating budget from linear or pure-social buys into this converged category. And for teams building out measurement frameworks, resources from HubSpot and Sprout Social on cross-channel attribution are a reasonable starting point, even if you’ll need to customize heavily for the TV-plus-creator use case.
Frequently Asked Questions
FAQ Section
What exactly is living room commerce?
Living room commerce refers to shopping activity initiated or completed through connected TV environments, including shoppable ads, QR-code checkouts, and live shopping events that stream to smart TVs and streaming devices rather than only mobile screens.
How is creator content different when it’s built for CTV instead of mobile?
CTV-native creator content typically needs stronger production values, slower pacing, and clearer visual calls to action, since viewers on a 10-foot screen interact differently than someone scrolling a phone with their thumb.
Can brands track ROI across CTV and creator content accurately?
Attribution is improving through device-graph matching and unified measurement platforms, but it remains less precise than mobile click tracking. Brands should treat CTV attribution as directional rather than exact until identity resolution technology matures further.
Do creators need different contracts or usage rights for CTV distribution?
Yes. Brands should explicitly negotiate CTV and connected device distribution rights in creator contracts, since many existing agreements only cover social platform usage and don’t anticipate television-scale distribution.
Which platforms are leading the convergence of CTV and creator content?
YouTube, Roku, Amazon Fire TV, and Samsung TV Plus have all built shoppable and creator-friendly ad formats specifically for connected TV environments, making them the most active testing grounds for this convergence right now.
Next step: audit whether your current creator briefs and contracts even mention CTV distribution. If they don’t, you’re leaving conversion revenue and usage rights on the table right when the living room is becoming the highest-value screen in the house.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →