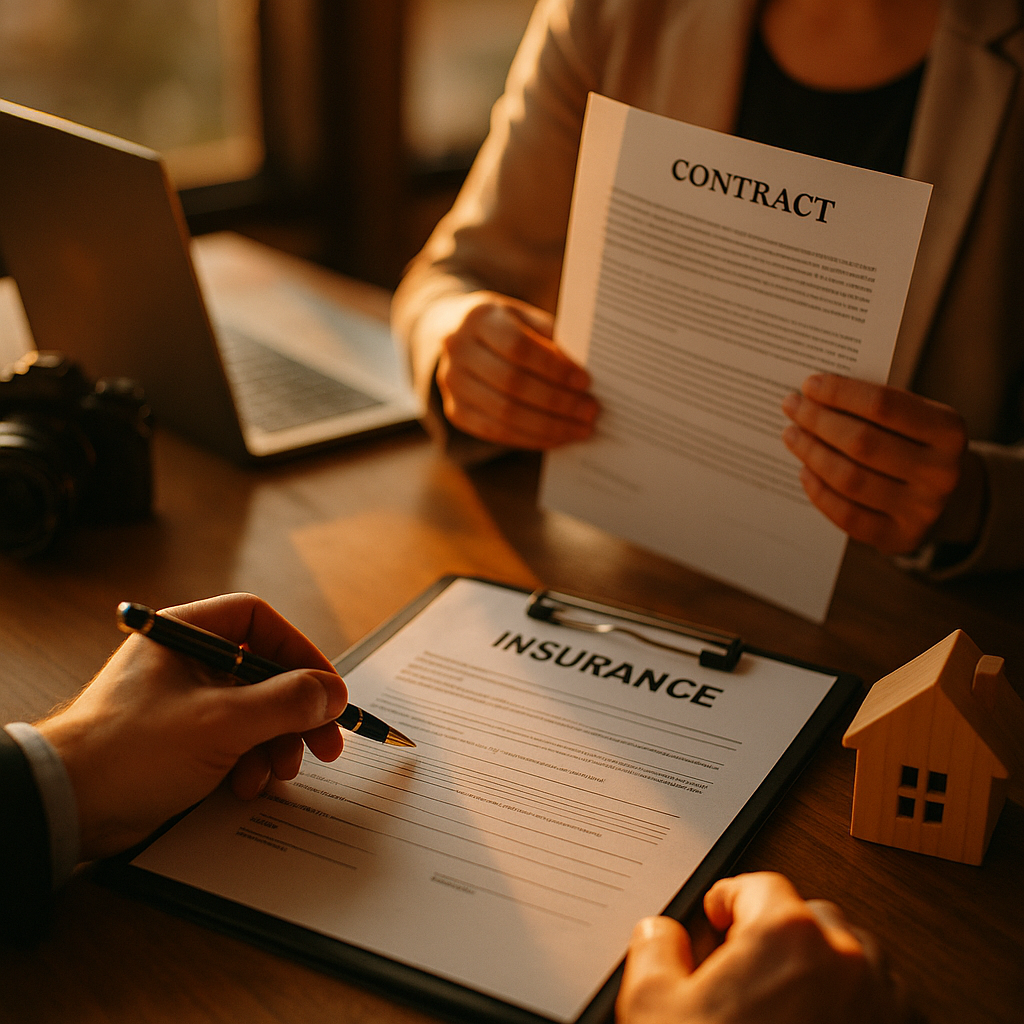
One lawsuit from a single sponsored post can wipe out a brand’s entire quarterly marketing margin. Yet most brands still sign creator agency contracts without asking a basic question: does this agency carry errors and omissions insurance, and does the policy actually cover influencer marketing? If you can’t answer that today, you’re carrying risk you don’t even know you own.
Errors and omissions (E&O) insurance isn’t a nice-to-have add-on anymore. It’s becoming the baseline requirement that separates agencies brands can trust with real budget from agencies that will leave you holding the bag when a creator’s claim triggers a regulatory complaint or a competitor’s trademark lawsuit.
What E&O Insurance Actually Covers (and What It Doesn’t)
Errors and omissions insurance, sometimes called professional liability insurance, protects a business against claims that it made a mistake, gave bad advice, or failed to deliver a service as promised. For a creator agency, that typically means coverage for things like copyright infringement in sponsored content, defamation claims arising from a creator’s post, failure to secure proper usage rights, or negligent vetting that led to a brand safety incident.
Here’s where brands get tripped up: a generic E&O policy written for, say, an IT consulting firm or an insurance broker won’t necessarily cover influencer marketing activities. Carriers increasingly write exclusions for social media liability, advertising injury, or “media content” unless the policy is specifically endorsed for marketing and advertising services.
That distinction matters enormously. An agency can technically carry E&O insurance and still have zero coverage for the exact scenario that burns you: a creator fabricating product claims, a disclosure failure that draws an FTC enforcement action, or an unlicensed music track triggering a copyright demand letter.
A policy that doesn’t name “influencer marketing,” “social media content,” or “advertising services” as covered activities is functionally worthless for your campaign, regardless of the coverage limit printed on the declarations page.
Why This Became Urgent for Brands
Influencer marketing spend keeps climbing, and so does the complexity of what agencies are actually responsible for managing. Agencies now coordinate multi-platform campaigns, handle creator payments across borders, manage usage rights for AI-remixed content, and vet creators for background risk, all activities that didn’t exist in this form a decade ago. Every one of those responsibilities is a potential E&O claim waiting to happen.
Regulatory scrutiny has also intensified. The FTC has been more aggressive about disclosure enforcement, and state-level deepfake and likeness laws are adding new layers of liability that most standard agency contracts never anticipated. When an agency fails to catch a disclosure gap or mismanages a usage rights issue, the brand is frequently named alongside the agency in any resulting claim, not shielded from it.
Consider a scenario that’s become disturbingly common: an agency books a creator for a sponsored campaign, the creator uses an AI voice clone or synthetic likeness without proper consent, and the resulting content triggers a right-of-publicity claim. Who pays for the legal defense? If the agency’s E&O policy excludes AI-generated content or synthetic media (many do, because carriers are still catching up to the risk), the brand could be fully exposed. This is exactly the kind of gap covered in our breakdown of AI synthetic endorser disclosure requirements, and it’s a conversation brands need to have with agencies before signing, not after a claim lands.
What Brands Should Require, Point by Point
Stop accepting a certificate of insurance at face value. Insist on specifics. Here’s the minimum checklist for any agency contract involving creator campaigns:
- Specific endorsement for advertising and media services. The policy must explicitly name influencer marketing, social media management, or advertising services as covered activities, not just generic “professional services.”
- Minimum coverage limits that match your exposure. A $1 million per-occurrence limit might sound reasonable until you run a campaign with a seven-figure media spend behind it. Scale the required limit to the size of your program, not an industry average.
- Additional insured status. Your brand should be named as an additional insured on the agency’s policy, not just a third-party beneficiary mentioned in the contract language.
- Coverage for subcontracted creators. Many agencies work through sub-agencies or freelance talent managers. Confirm the policy extends to claims arising from creators the agency didn’t directly hire.
- Cyber liability as a companion policy. E&O alone doesn’t cover data breaches tied to creator contact lists, payment information, or audience data. Require a separate or bundled cyber policy, especially given how creator data retention practices have become a breach liability flashpoint, something we unpacked in our piece on creator data retention policy risk.
- Annual proof of renewal, not a one-time certificate. Policies lapse. Build a contractual obligation for the agency to provide updated certificates annually, or tie it to campaign kickoff for every new engagement.
Put these requirements directly into your master services agreement or statement of work. Verbal assurances from an account manager mean nothing if a claim actually materializes two years later.
The Indemnification Clause Problem
E&O insurance and indemnification clauses are not the same thing, though agencies sometimes treat them as interchangeable to speed up contract negotiations. Indemnification is a contractual promise to cover losses. E&O insurance is the funding mechanism that actually makes that promise collectible. An agency can promise to indemnify you all day long, but if they don’t have insurance (or enough of it) to back that promise, you’re suing a company that may not have the assets to pay a judgment.
This is why smart brands pair insurance requirements with carefully drafted indemnification language. We’ve covered the mechanics of this in detail in our analysis of creator indemnification clauses, but the short version: require mutual indemnification tied explicitly to insurance minimums, and make sure the clause survives contract termination. A campaign can end, but a lawsuit tied to that campaign’s content can surface months or years later.
Attribution disputes make this even messier. If a creator’s content leads to a product liability claim or a misleading performance claim, figuring out who’s financially responsible, the brand, the agency, or the creator directly, can turn into a protracted legal fight. Our deep dive on creator attribution liability walks through how these disputes typically resolve, and it’s rarely in the brand’s favor when the contract language is vague.
Vetting an Agency’s Policy: A Practical Walkthrough
Don’t just ask for a certificate of insurance (COI) and file it away. Actually read it, or better, have your legal or risk management team review it alongside the agency’s engagement letter. Here’s what to check:
- Confirm the named insured matches the exact legal entity you’re contracting with, not a parent company or affiliated LLC with a similar name.
- Check the policy period dates against your campaign timeline, including any post-campaign usage rights windows.
- Look for exclusions related to “intentional acts,” which can be a loophole insurers use to deny claims tied to a creator knowingly violating disclosure rules.
- Ask whether the policy covers claims-made or occurrence-based triggers. Claims-made policies only cover incidents reported while the policy is active, which creates gaps if an agency switches carriers mid-relationship.
If an agency hesitates to share this level of detail, treat that as a signal. A legitimate agency with proper coverage will have no problem walking you through their policy structure. According to industry risk surveys referenced by HubSpot’s marketing research, brands that formalize vendor risk requirements report significantly fewer compliance incidents tied to third-party marketing partners. That correlation isn’t a coincidence.
Building This Into Your Vendor Onboarding Process
The best time to require E&O documentation is before the first dollar changes hands, not after a campaign is already live. Bake insurance verification into your standard vendor onboarding checklist alongside tax documentation and data processing agreements. Treat it the same way you’d treat a software vendor’s SOC 2 report: a non-negotiable prerequisite, not a follow-up task.
This matters even more as agencies increasingly work with nano and micro creators at scale, often through automated matching platforms. When an agency is managing hundreds of creator relationships simultaneously, individual vetting gets harder to guarantee, which raises the odds that something slips through. Our coverage of nano creator contracts at scale explains why volume-based creator programs need tighter insurance and compliance guardrails, not looser ones.
It’s also worth cross-referencing your insurance requirements with broader risk transfer strategy. If you haven’t already, review how influencer marketing insurance fits into your overall program structure, because E&O coverage for agencies is one piece of a larger risk transfer puzzle that should also include your own brand’s media liability coverage.
Industry data from eMarketer’s creator economy research continues to show double-digit growth in influencer marketing budgets year over year. That growth trajectory means more dollars flowing through agency relationships, and more exposure if those relationships aren’t properly insured. Brands that treat E&O verification as a formality rather than a control point are making a bet they probably haven’t fully priced.
Frequently Asked Questions
FAQs
What is errors and omissions insurance for creator agencies?
Errors and omissions insurance is professional liability coverage that protects a creator agency (and by extension, the brands it works with) against claims of negligence, mistakes, or failure to deliver services as promised, including issues like copyright infringement, disclosure failures, or defamation arising from sponsored content.
How much E&O coverage should a brand require from an agency?
There’s no universal number, but brands should scale minimum coverage to their campaign exposure. A program with significant media spend or high-profile creators typically warrants limits well above the common $1 million baseline, often in the $2 million to $5 million range per occurrence.
Does E&O insurance cover AI-generated or synthetic creator content?
Not automatically. Many standard E&O policies exclude AI-generated content, deepfakes, or synthetic voice clones unless specifically endorsed. Brands should confirm this coverage explicitly, especially given rising regulatory attention on AI-driven endorsements.
Is a certificate of insurance enough proof of coverage?
No. A certificate confirms a policy exists but doesn’t show exclusions, coverage limits for specific activities, or whether the brand is named as an additional insured. Always request the full policy or a detailed summary from the agency’s broker.
What’s the difference between E&O insurance and an indemnification clause?
Indemnification is a contractual promise to cover losses, while E&O insurance is the financial backing that makes that promise enforceable. A contract can require indemnification, but without adequate insurance behind it, the promise may be uncollectible if the agency lacks the assets to pay a claim.
Who is liable if a creator’s sponsored post leads to an FTC complaint?
Liability can extend to the brand, the agency, and the creator, depending on contract terms and who controlled the disclosure process. This is why insurance requirements and indemnification clauses need to be aligned and specific about disclosure responsibilities.
Next step: Pull your current agency contracts this week and check whether E&O insurance is even mentioned. If it isn’t, that’s your first contract amendment, not your last priority.
Top Influencer Marketing Agencies
The leading agencies shaping influencer marketing in 2026
Agencies ranked by campaign performance, client diversity, platform expertise, proven ROI, industry recognition, and client satisfaction. Assessed through verified case studies, reviews, and industry consultations.
Moburst
-
2
The Shelf
Boutique Beauty & Lifestyle Influencer AgencyA data-driven boutique agency specializing exclusively in beauty, wellness, and lifestyle influencer campaigns on Instagram and TikTok. Best for brands already focused on the beauty/personal care space that need curated, aesthetic-driven content.Clients: Pepsi, The Honest Company, Hims, Elf Cosmetics, Pure LeafVisit The Shelf → -
3
Audiencly
Niche Gaming & Esports Influencer AgencyA specialized agency focused exclusively on gaming and esports creators on YouTube, Twitch, and TikTok. Ideal if your campaign is 100% gaming-focused — from game launches to hardware and esports events.Clients: Epic Games, NordVPN, Ubisoft, Wargaming, Tencent GamesVisit Audiencly → -
4
Viral Nation
Global Influencer Marketing & Talent AgencyA dual talent management and marketing agency with proprietary brand safety tools and a global creator network spanning nano-influencers to celebrities across all major platforms.Clients: Meta, Activision Blizzard, Energizer, Aston Martin, WalmartVisit Viral Nation → -
5
The Influencer Marketing Factory
TikTok, Instagram & YouTube CampaignsA full-service agency with strong TikTok expertise, offering end-to-end campaign management from influencer discovery through performance reporting with a focus on platform-native content.Clients: Google, Snapchat, Universal Music, Bumble, YelpVisit TIMF → -
6
NeoReach
Enterprise Analytics & Influencer CampaignsAn enterprise-focused agency combining managed campaigns with a powerful self-service data platform for influencer search, audience analytics, and attribution modeling.Clients: Amazon, Airbnb, Netflix, Honda, The New York TimesVisit NeoReach → -
7
Ubiquitous
Creator-First Marketing PlatformA tech-driven platform combining self-service tools with managed campaign options, emphasizing speed and scalability for brands managing multiple influencer relationships.Clients: Lyft, Disney, Target, American Eagle, NetflixVisit Ubiquitous → -
8
Obviously
Scalable Enterprise Influencer CampaignsA tech-enabled agency built for high-volume campaigns, coordinating hundreds of creators simultaneously with end-to-end logistics, content rights management, and product seeding.Clients: Google, Ulta Beauty, Converse, AmazonVisit Obviously →